Showing 109 of 109on this page. Filters & sort apply to loaded results; URL updates for sharing.109 of 109 on this page
Corporate Losses When the Difference Between CVAR and VAR Gets Too ...
Example of VaR and CVaR at risk level β = 0.9. | Download Scientific ...
Properties of VaR and CVaR Risk Measures in High-Frequency Domain: Long ...
Find a REALTOR® | CVAR Central Valley Association of REALTORS®
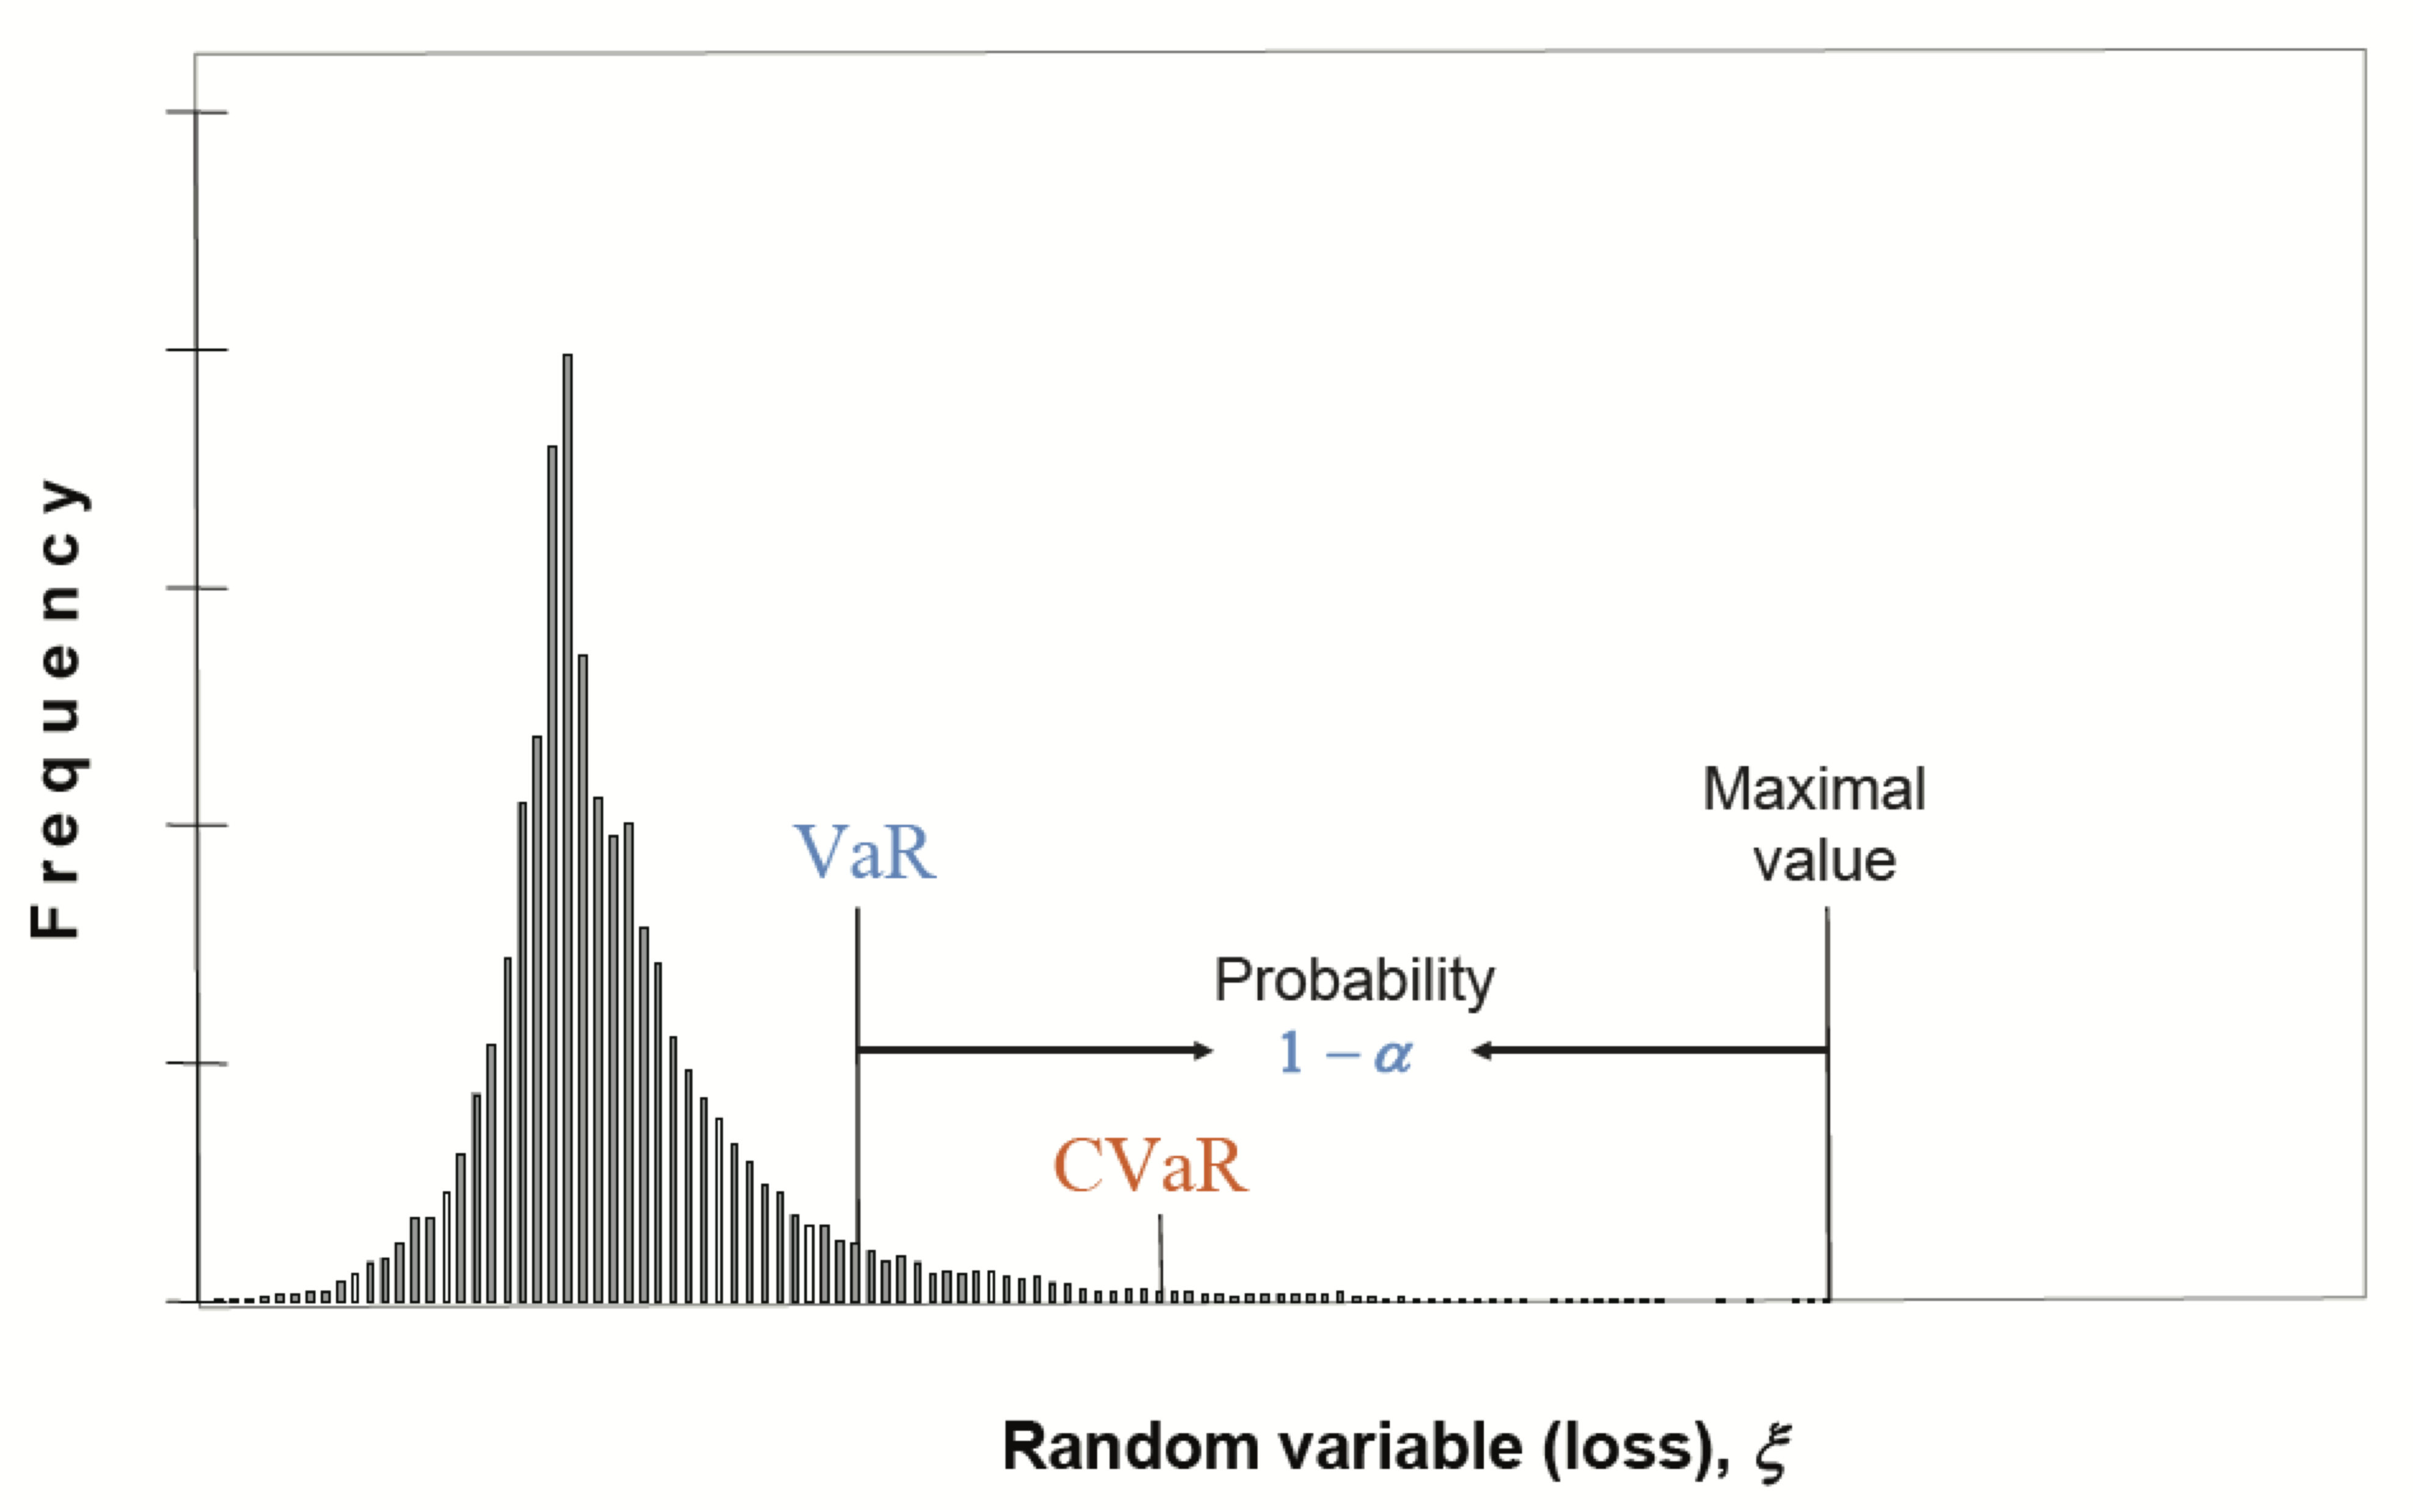
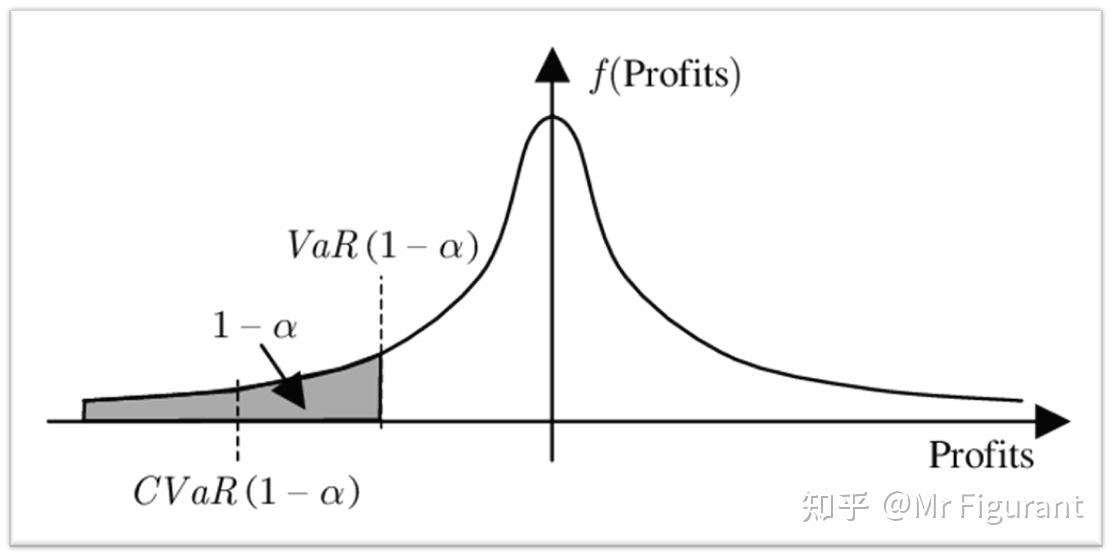
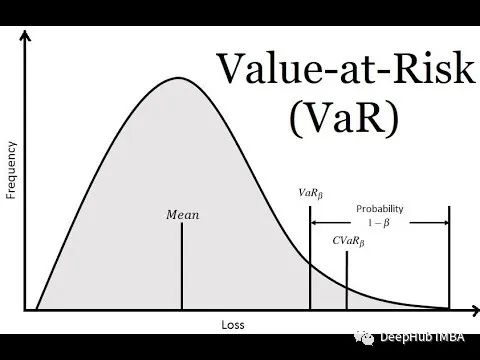
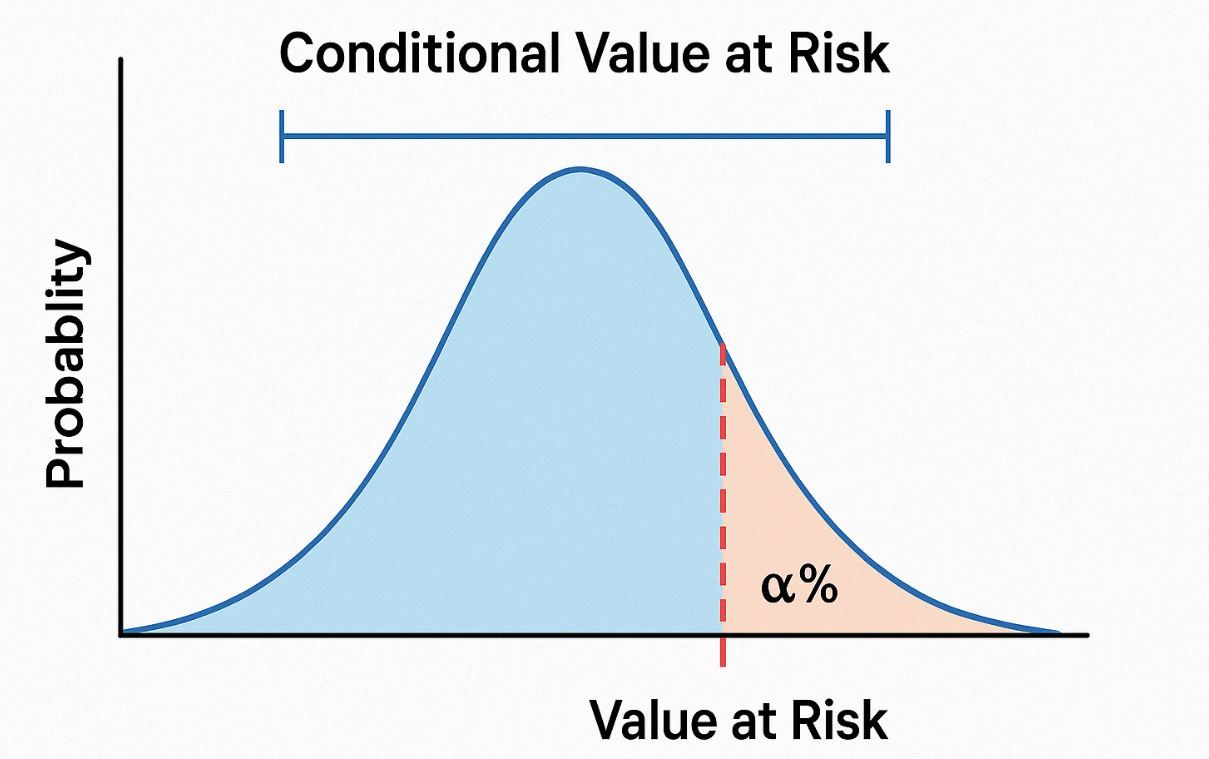
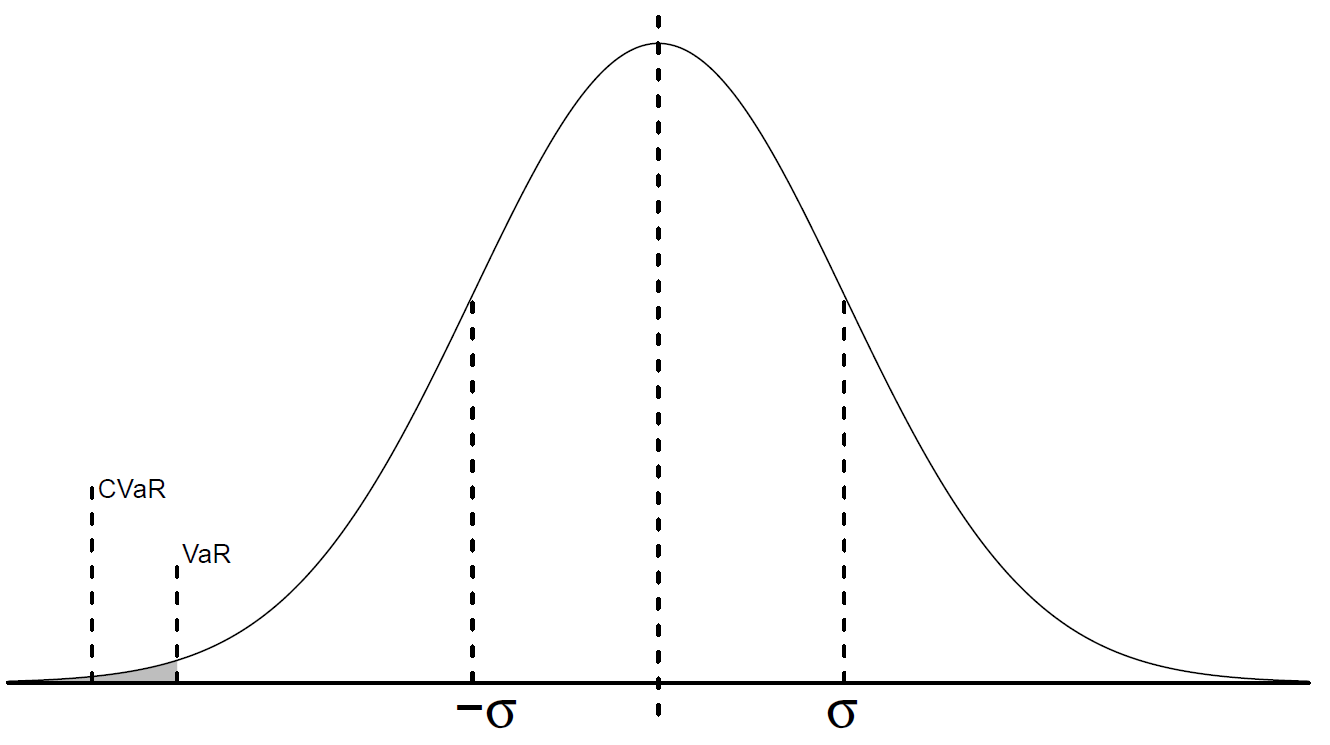
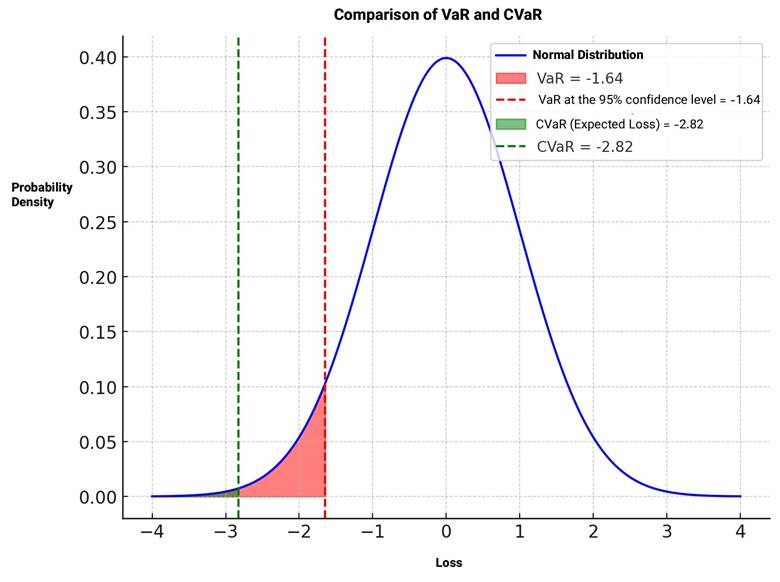
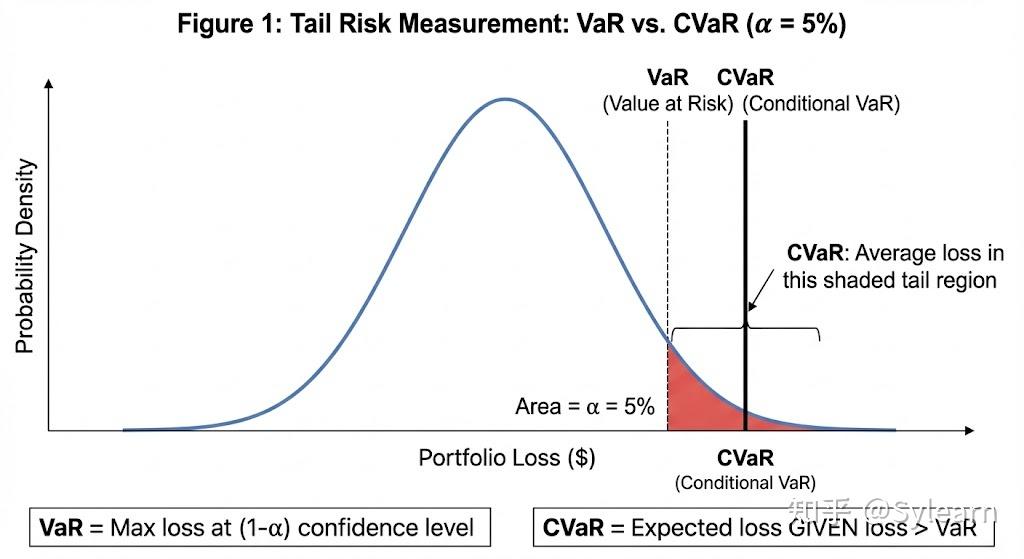
A visualization of VaR and CVaR concepts. | Download Scientific Diagram
represents the CVaR in terms of costs. | Download Scientific Diagram
VaR, CVaR and deviations adapted from Sarykalin et al. [74]. | Download ...
Portfolio Optimization with CVaR - My Notes
VaR y CVaR para medir el riesgo en tu trading - Rubén Martínez
Buy Why is CVaR Superior to VaR?: A Unified Framework for Mean-Risk ...
New Robust Reward‐Risk Ratio Models with CVaR and Standard Deviation ...
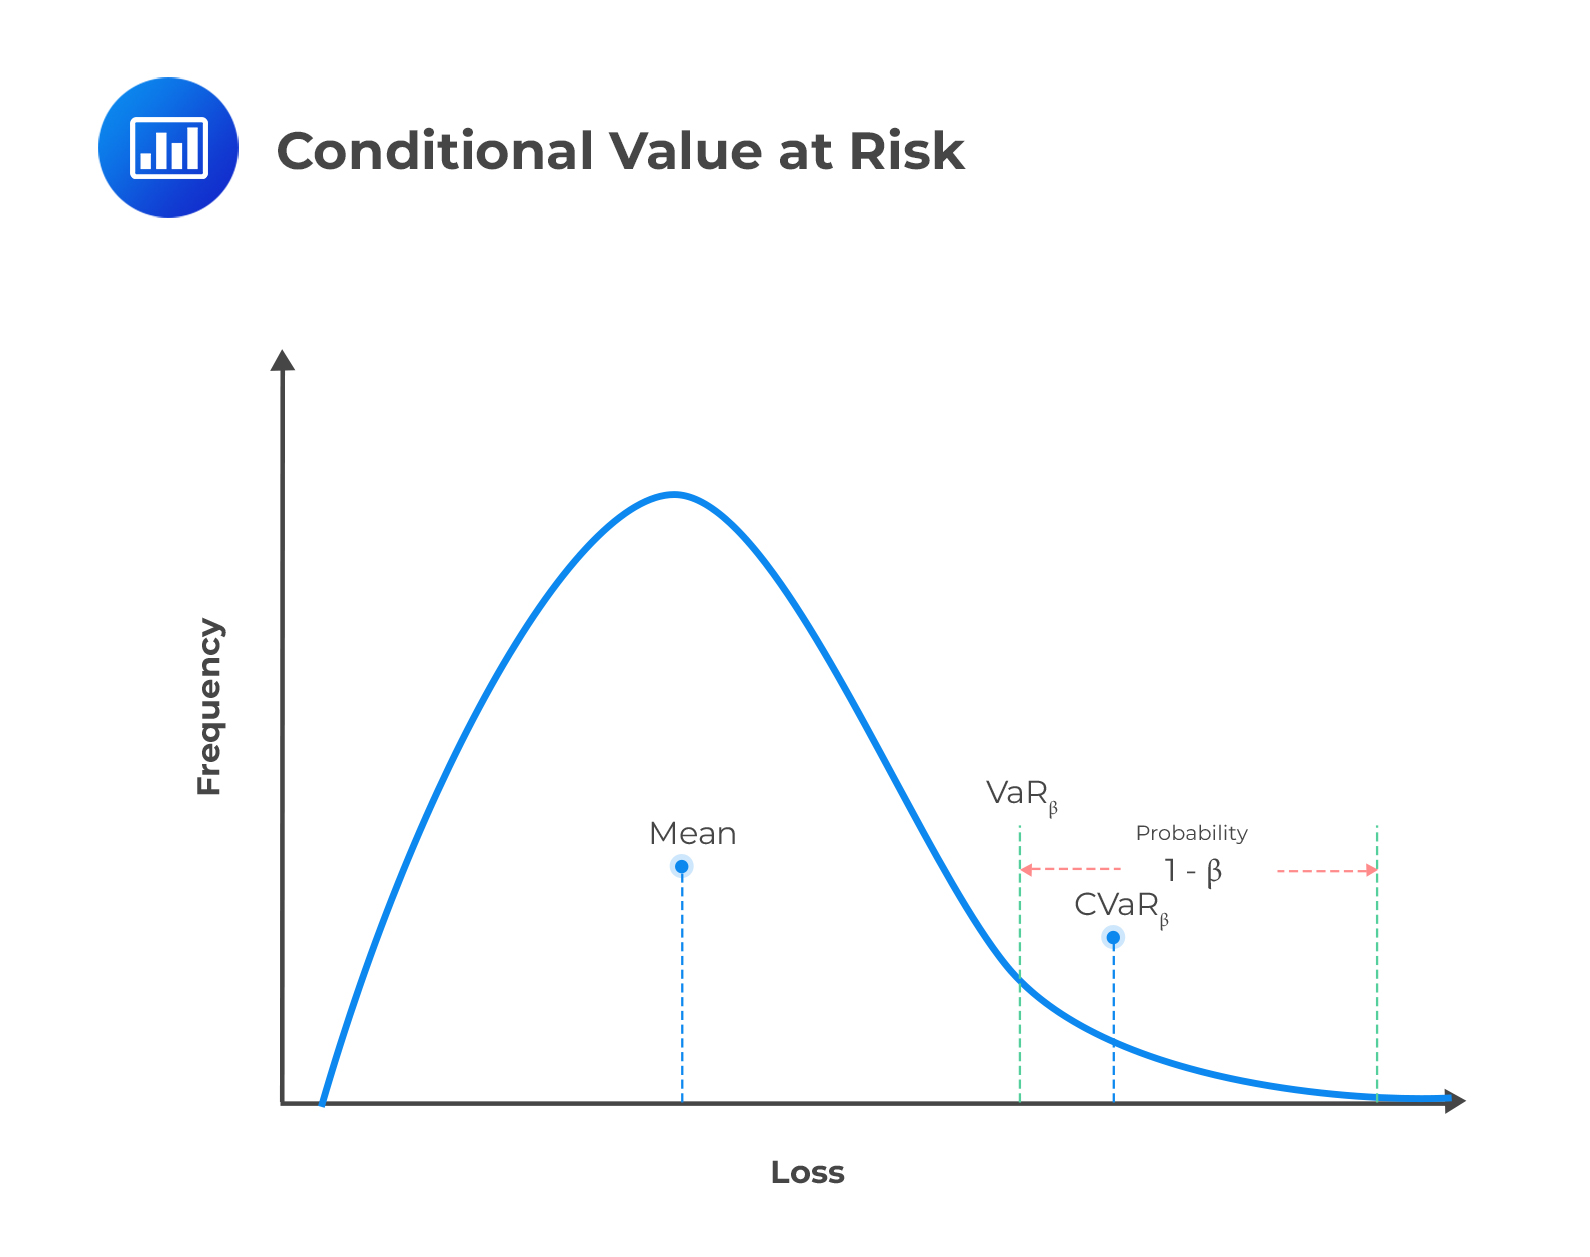
Graphical representation of VaR and CVaR | Download Scientific Diagram
VaR and CVaR Representation [35]. | Download Scientific Diagram
Conditional Value-at-Risk CVaR – pensionfund.cern.ch
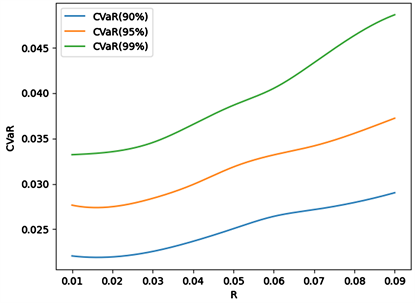
VaR and CVaR Optimal Values for Various Confidence Levels | Download ...
Mean returns and 99% CVaR of 10 portfolios in each case | Download ...
(PDF) Properties of VaR and CVaR Risk Measures in High-Frequency Domain ...
Risk-return out-of-sample frontier using CVaR as a risk metric and ...
VaR and CVaR representation [12] | Download Scientific Diagram
CVaR and VaR representation. | Download Scientific Diagram
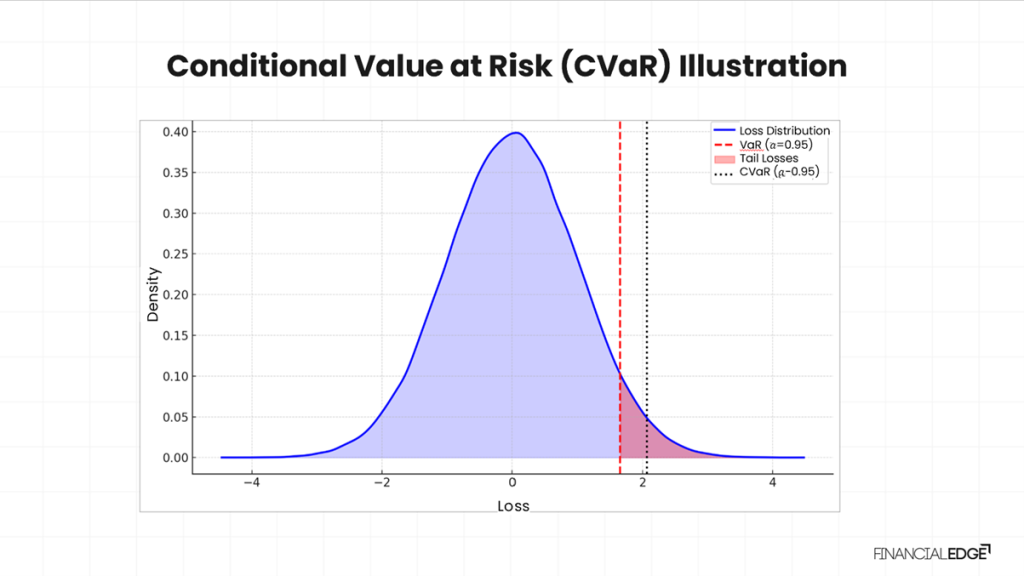
Illustration of mean and CVaR with α = 0.95 for an example distribution ...
CVaR at mean of the sampling distribution and trajectory of risk level ...
Variations of the objective and CVaR functions for different values of ...
CFA2级:拓展:什么是风险价值 VaR? - 知乎
三种常用的风险价值(VaR)计算方法总结 - deephub - 博客园
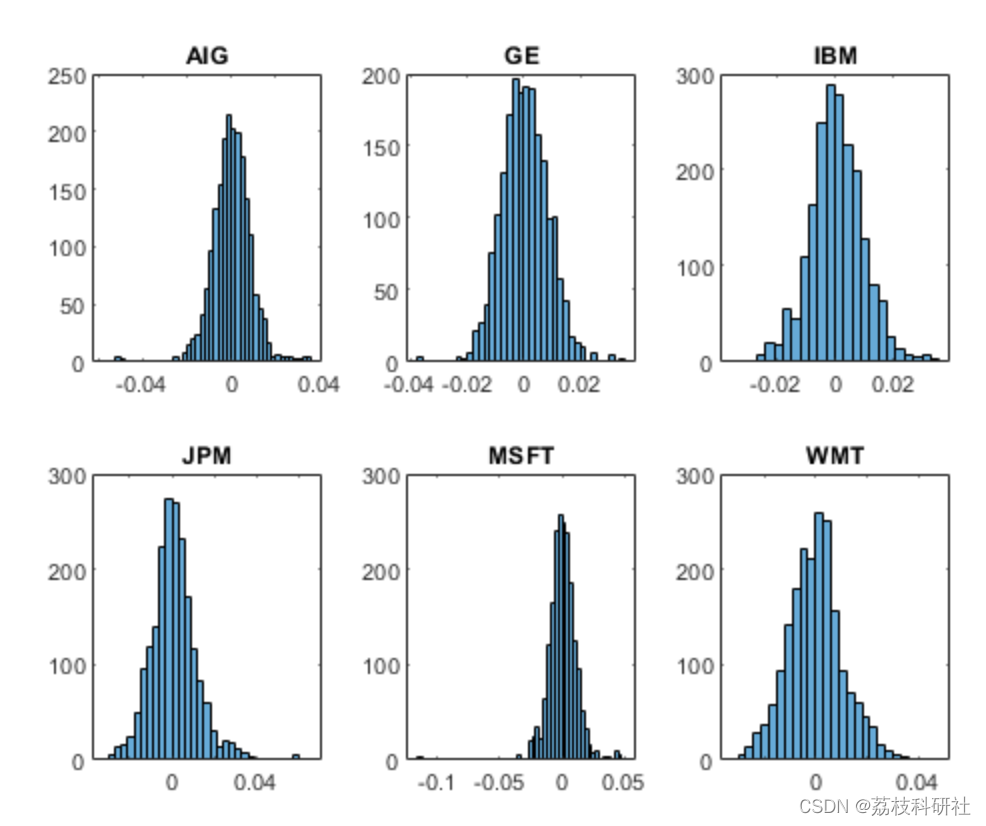
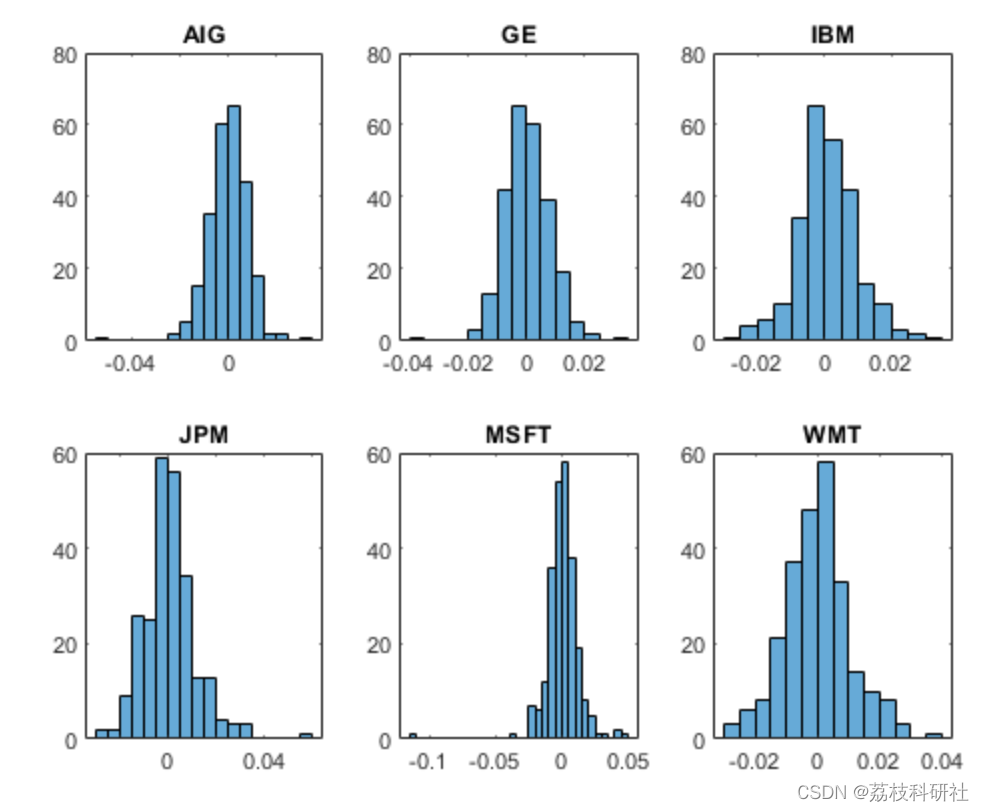
使用投资组合CVaR对象进行条件风险价值(CVaR)投资组合优化(Matlab代码实现)-CSDN博客
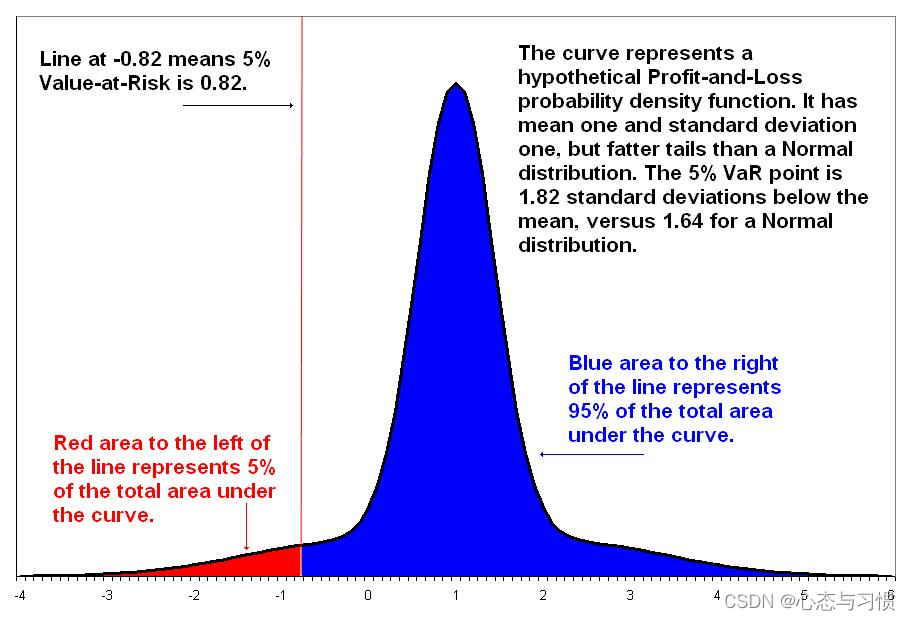
风险价值VaR、CVaR与ES_es 风险价值-CSDN博客
条件风险价值模型(Conditional Value at Risk,CVaR)_conditional value-at-risk-CSDN博客
VaR 与 CVaR_var和cvar-CSDN博客
均值-CVaR模型在资产配置中的应用研究——基于A股市场的分析
使用投资组合CVaR对象进行条件风险价值(CVaR)投资组合优化(Matlab代码实现)_投资组合代码-CSDN博客
使用投资组合CVaR对象进行条件风险价值(CVaR)投资组合优化(Matlab代码实现)_cvar的计算过程-CSDN博客
条件风险价值模型(Conditional Value at Risk,CVaR)_条件在线价值模型-CSDN博客
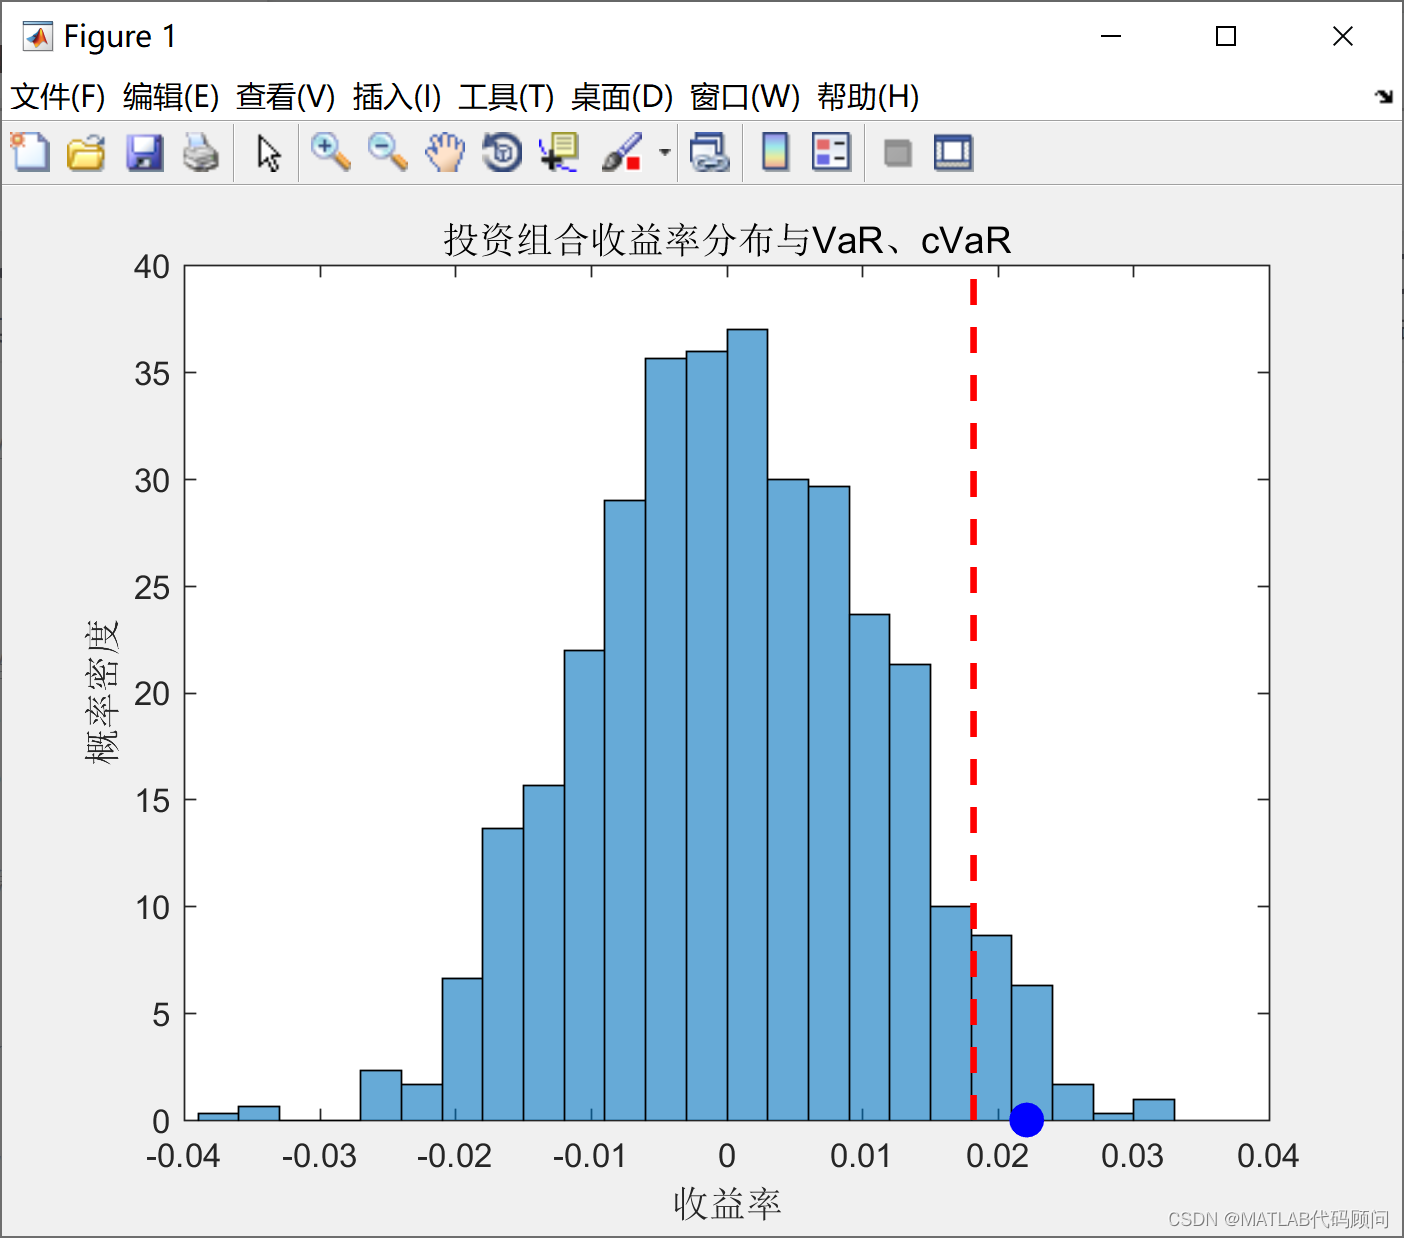
MATLAB计算投资组合的cVaR和VaR_均值var的投资组合模型 matlab-CSDN博客
VaR和CVaR举例说明_笔记转载-CSDN博客
基于条件风险价值CVaR的微网动态定价与调度策略(Matlab代码实现) - 荔枝科研社 - 博客园
【条件风险价值CVaR】【蒙特卡洛信用价值风险模拟】信用价值风险(Credit-VaR)对一个由6只直接债券组成的虚拟投资组合(Matlab ...
条件风险价值CVaR_条件风险值-CSDN博客
条件风险价值CVaR内容介绍(MATLAB例程)-CSDN博客
基于条件风险价值CVaR的微网动态定价与调度策略(Matlab代码实现)-CSDN博客
比较CVaR最优投资组合与均值-方差投资组合以及其他模型,包括全局最小方差(GMVP)和市场投资组合(Matlab代码实现)-CSDN博客
【条件风险价值CVaR】【蒙特卡洛信用价值风险模拟】信用价值风险(Credit-VaR)对一个由6只直接债券组成的虚拟投资组合附Matlab ...
基于条件风险价值CVaR的微网 虚拟电厂多场景随机规划 - 王曲 - 博客园
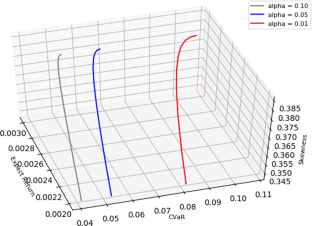
Portfolio analysis with mean-CVaR and mean-CVaR-skewness criteria based ...
基于条件风险价值CVaR的微网动态定价与调度策略附Matlab代码_cvar 模型-CSDN博客
基于条件风险价值CVaR的微网动态定价与调度策略(Matlab代码实现)_cvar条件风险价值 matlab代码-CSDN博客
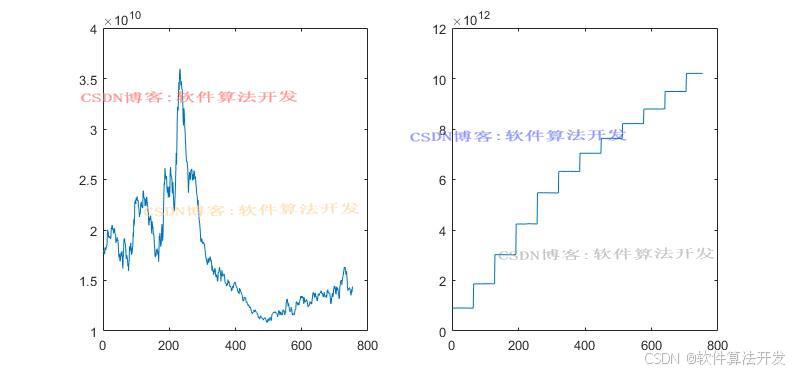
基于GARCH-Copula-CVaR模型的金融系统性风险溢出效应matlab模拟仿真_garch-copula-covar-CSDN博客
基于GARCH-Copula-CVaR模型的金融系统性风险溢出效应matlab模拟仿真-阿里云开发者社区
VaR计算及其改进方法总结(FRM二级-市场风险) - 知乎
基于条件风险价值CVaR的微网动态定价与调度策略(Matlab代码实现)_条件风险cvar代码matlab-CSDN博客
This work defines two versions of Conditional Value at Risk (CVaR) to ...
Conditional Value at Risk Explained - Free Excel Template
Capital at Risk vs Value at Risk: Your Investment Risk - Phemex Academy
(PDF) Value- at-Risk vs Conditional Value-at-Risk in Risk Management ...
Graphical illustration of conditional value at risk (CVaR) in a ...
Wat is Conditional Value at Risk (CVaR)? - Beleggen for Dummies
Value at Risk (VaR) and Conditional Value at Risk (CVaR) | Download ...
GitHub - caesarw0/CVAR_analysis: Shows the basic value at risk (VAR ...
Conditional Value At Risk: Formula and Examples
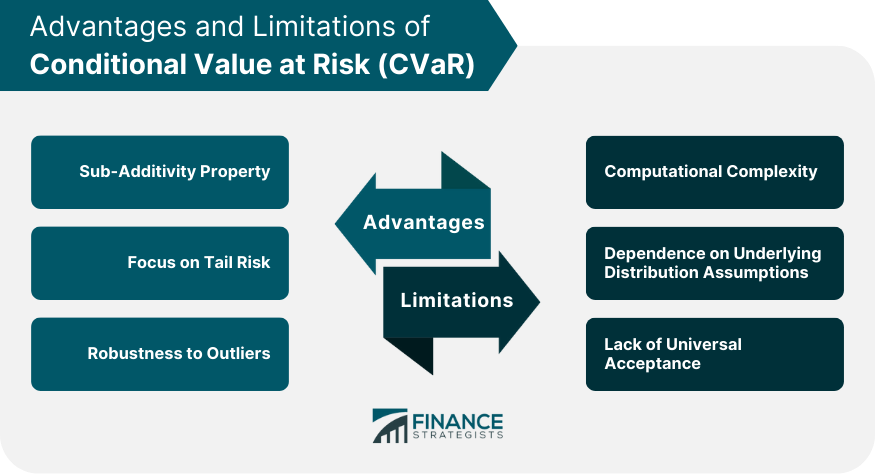
Conditional Value at Risk (CVaR) | Meaning, Pros, and Cons
Portfolio Optimization using Conditional Value at Risk | Thomas T. Bjerring
Giá trị chịu rủi ro có điều kiện (Conditional Value at Risk - CVaR) là ...
This work defines conditional value at risk (CVaR) to capture worst ...
What Is Value at Risk (VaR)? A Complete Guide to Calculating Maximum Loss
Conditional Value at Risk (CVaR) Portfolio Optimization - MATLAB
Conditional Value at Risk (CVaR) | AwesomeFinTech Blog
量化交易中的数学基础 - 知乎
10.2 Alternative Risk Measures | Portfolio Optimization
An illustration of risk measures: VaR and CVaR. | Download Scientific ...
Conditional Value at Risk(CVaR) - Enhancing Risk Assessment with ...
An Introduction to Value at Risk Methodologies | QuantPedia
Conditional Value At Risk Calculator – HAVJ
What Is An Example Of A Cvar? _ Conditional Value At Risk (CVaR) – IGUNK
What is Conditional Value at Risk (CVaR)? | Investment U
Relationship between VaR and CVaR. | Download Scientific Diagram
(PDF) Integration of Conditional Value-at-Risk (CVaR) in Multi ...
Conditional value‐at‐risk (CVaR) | Download Scientific Diagram
Expected profit and conditional value at risk (CVaR) of producer versus ...
GitHub - pos5231/Var-Cvar: Calculate and Value at Risk (VaR) and ...
Portfolio Var And Cvar. Scenario – IQFDW
Graphical representation of VaR and CVaR. | Download Scientific Diagram
cvar: Compute Expected Shortfall and Value at Risk for Continuous ...
Expected profit versus conditional value at risk (CVaR) | Download ...
[1901.00114] Closing the gap towards end-to-end autonomous vehicle system