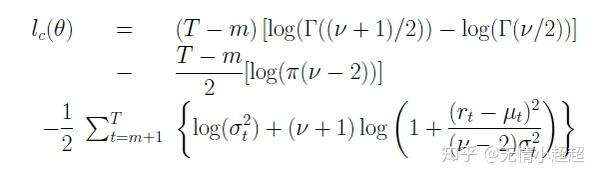Showing 120 of 120on this page. Filters & sort apply to loaded results; URL updates for sharing.120 of 120 on this page
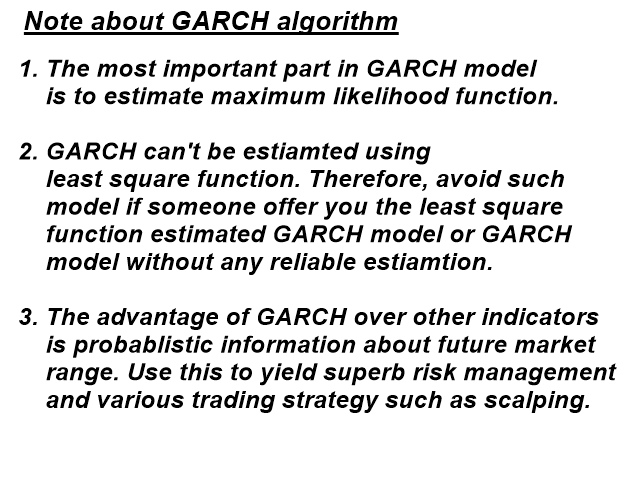
GARCH Indicator
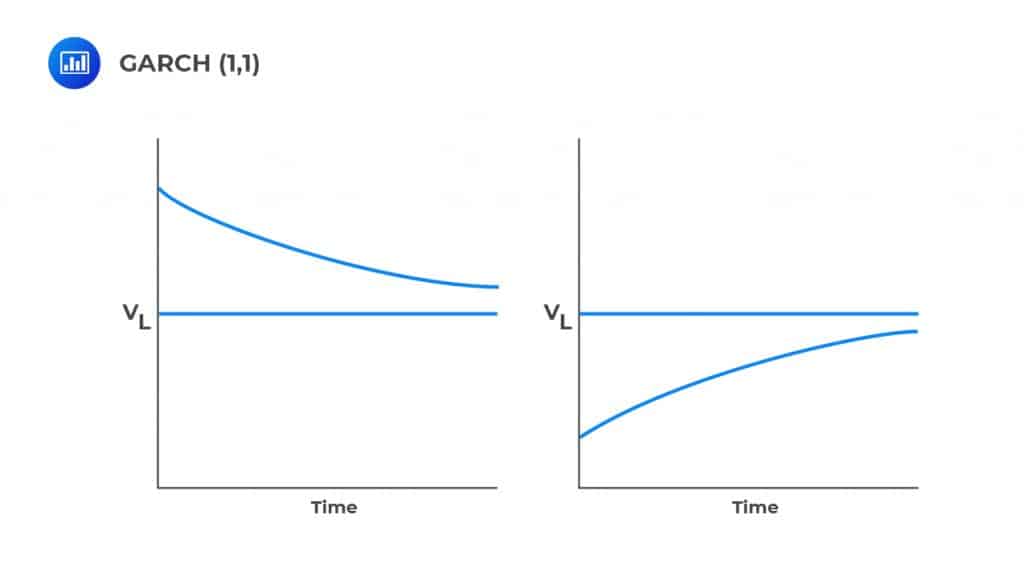
GARCH (1,1) - CFA, FRM, and Actuarial Exams Study Notes
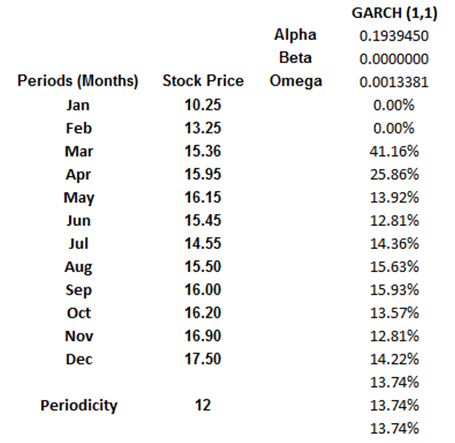
GARCH - Tutorial and Excel Spreadsheet
The GARCH equation for volatility prediction | R
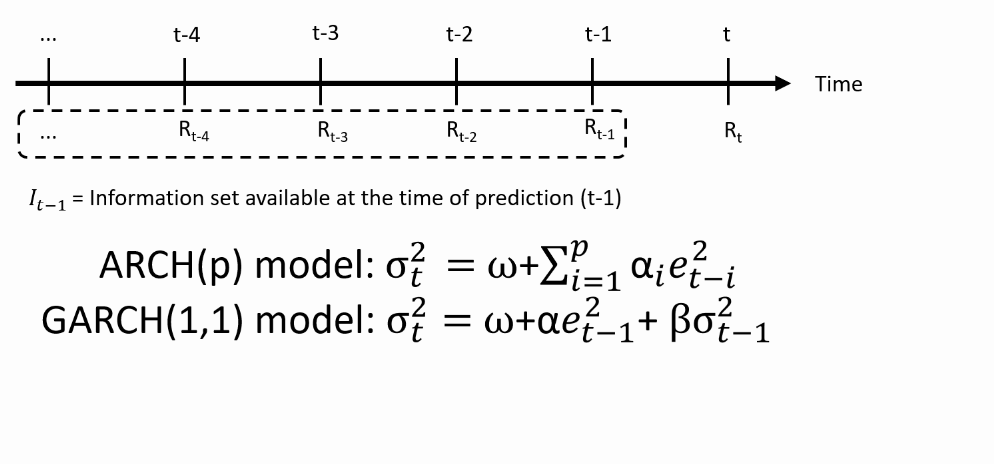
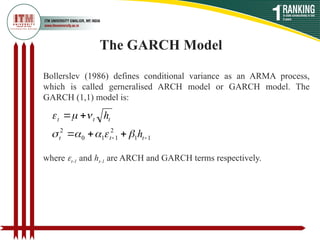
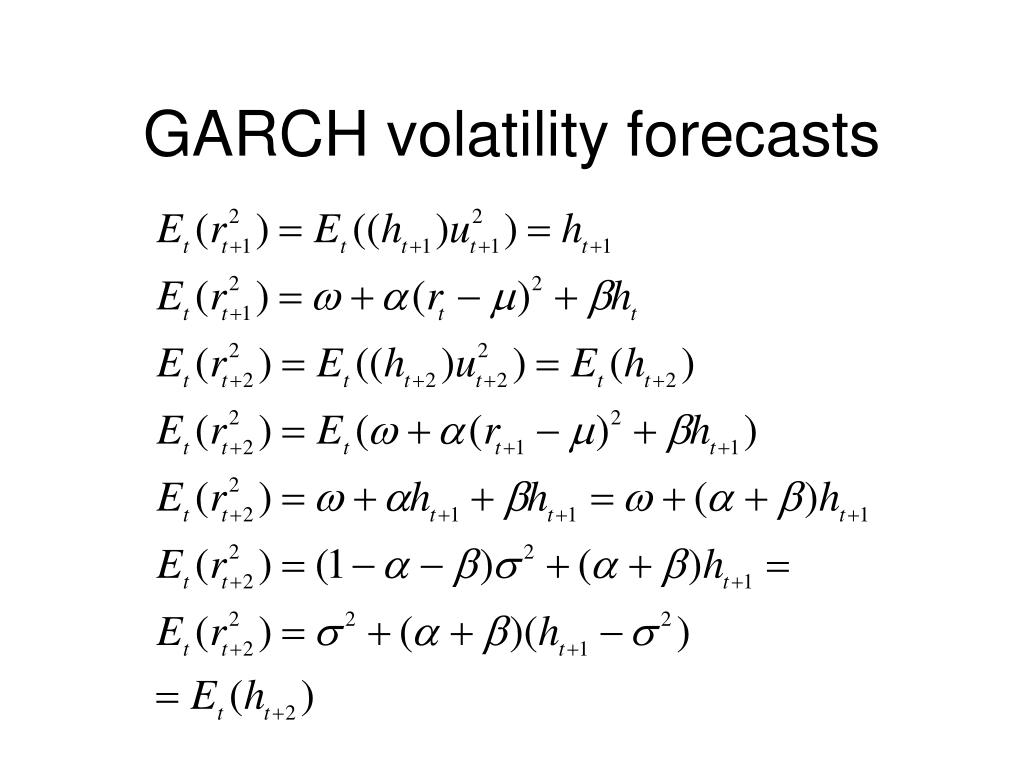
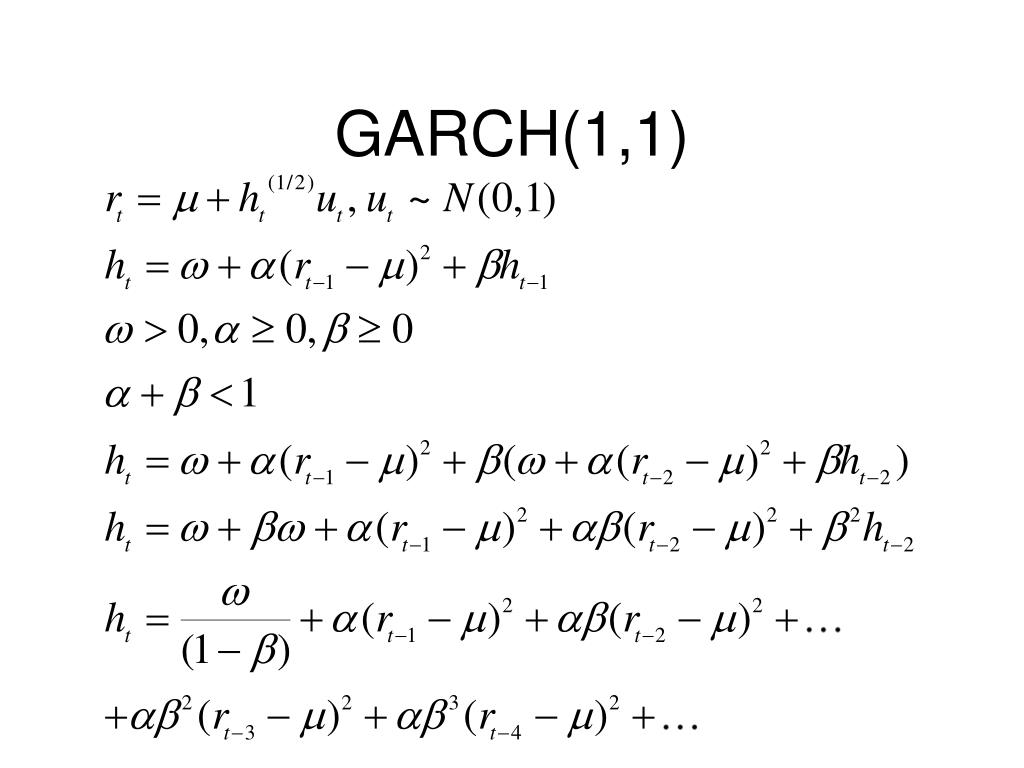
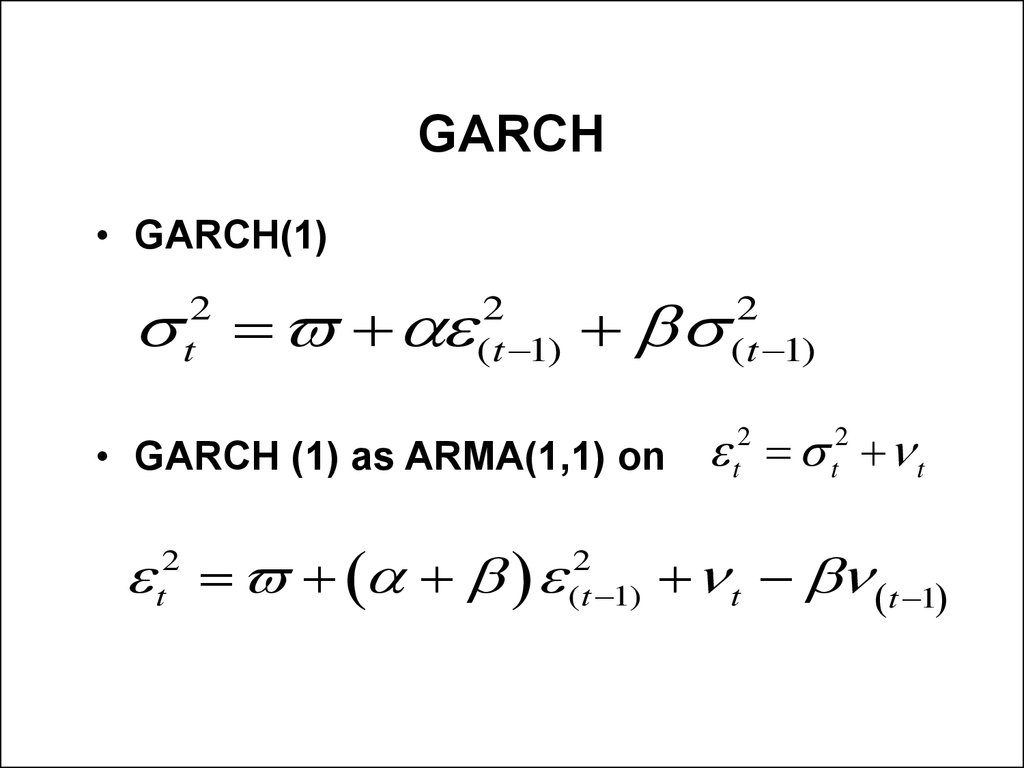
Financial econometrics xiii garch
What is a GARCH Model? – datawookie
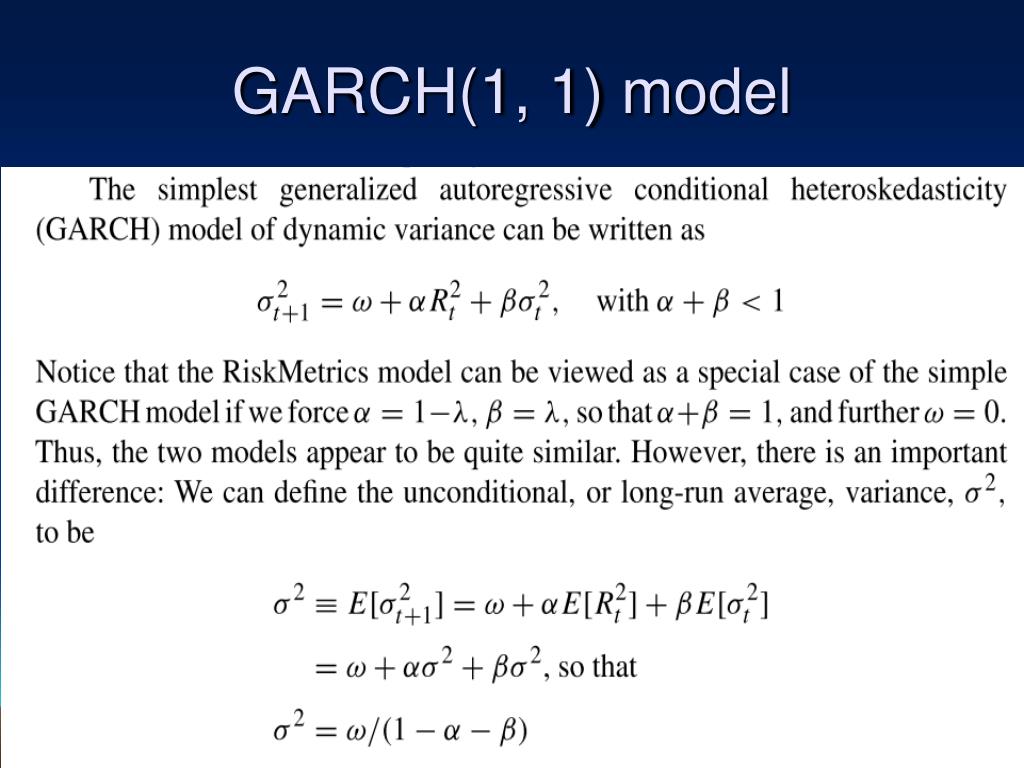
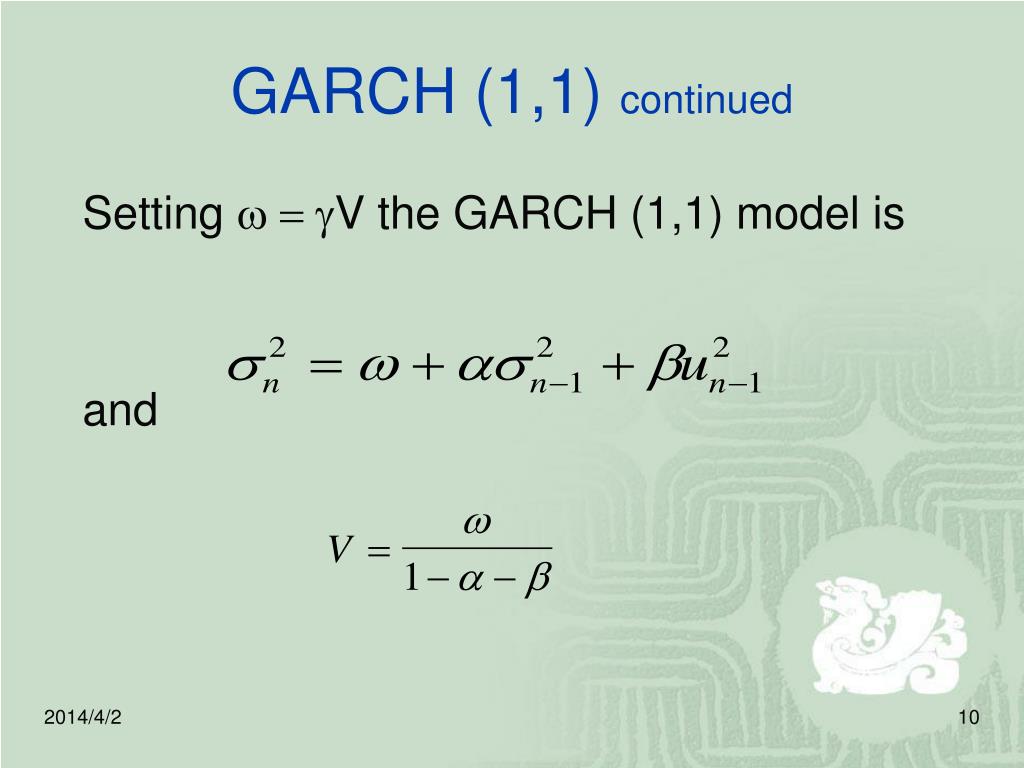
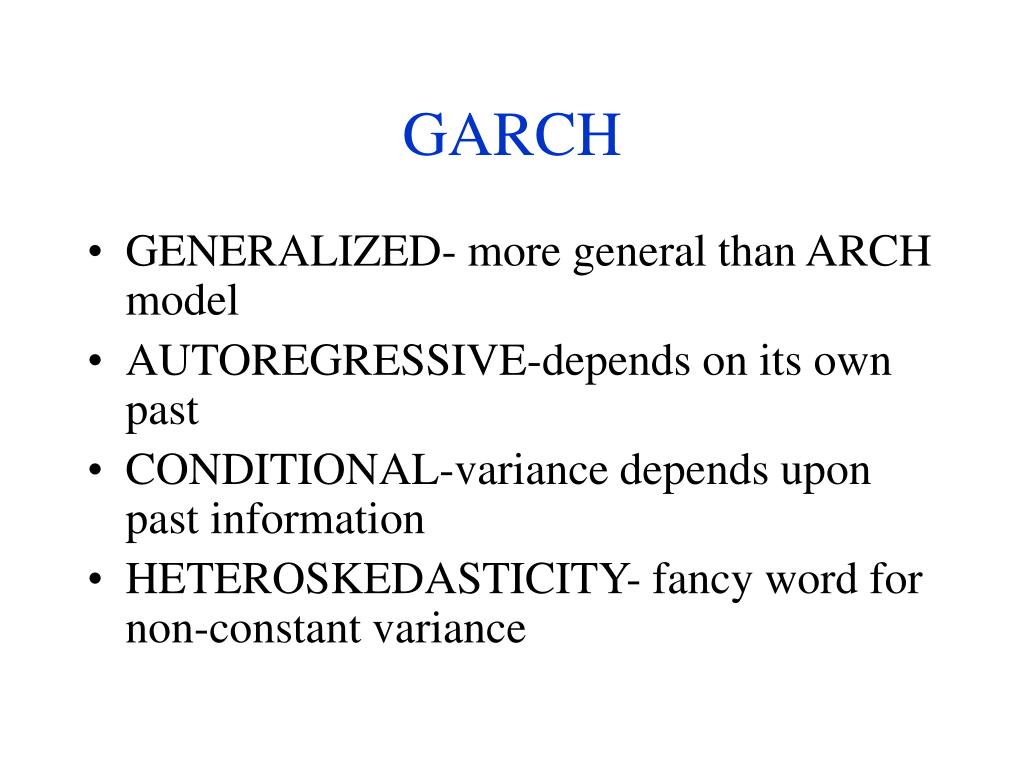
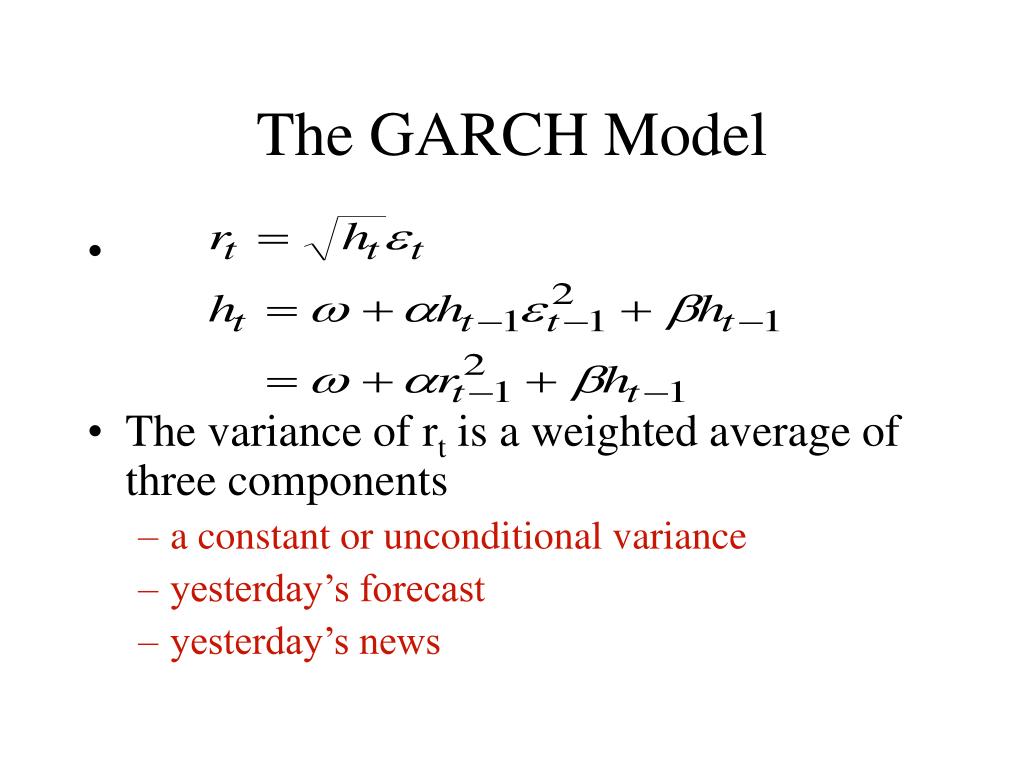
PPT - Week 10: VaR and GARCH model PowerPoint Presentation, free ...
GARCH Analysis on Volatility Patterns | EODHD APIs Academy
GARCH Model Volatility Forecasting Financial Markets PPT Sample ST AI ...
Modèle Garch Explication Simple – XLRROH
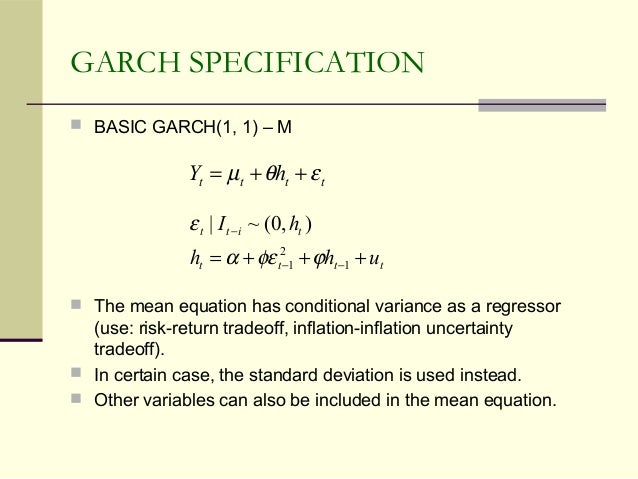
Unit 4 ARCH & GARCH Models for Time Series.ppt
Sample | Volatility Modelling and Forecasting Using GARCH
Garch (1, 1) the Figure As can be seen from the Figure 5 above, the ...
Indicators: GARCH Indicator - Industrial Level Volatility Estimator ...
Comparison between GARCH (1.1) Estimated Volatility vs. Unconditional ...
A cheat sheet of GARCH models used in Quant Finance. The GARCH model is ...
PPT - Predicting volatility: a comparative analysis between GARCH ...
Time-Varrying Volatility with GARCH Model
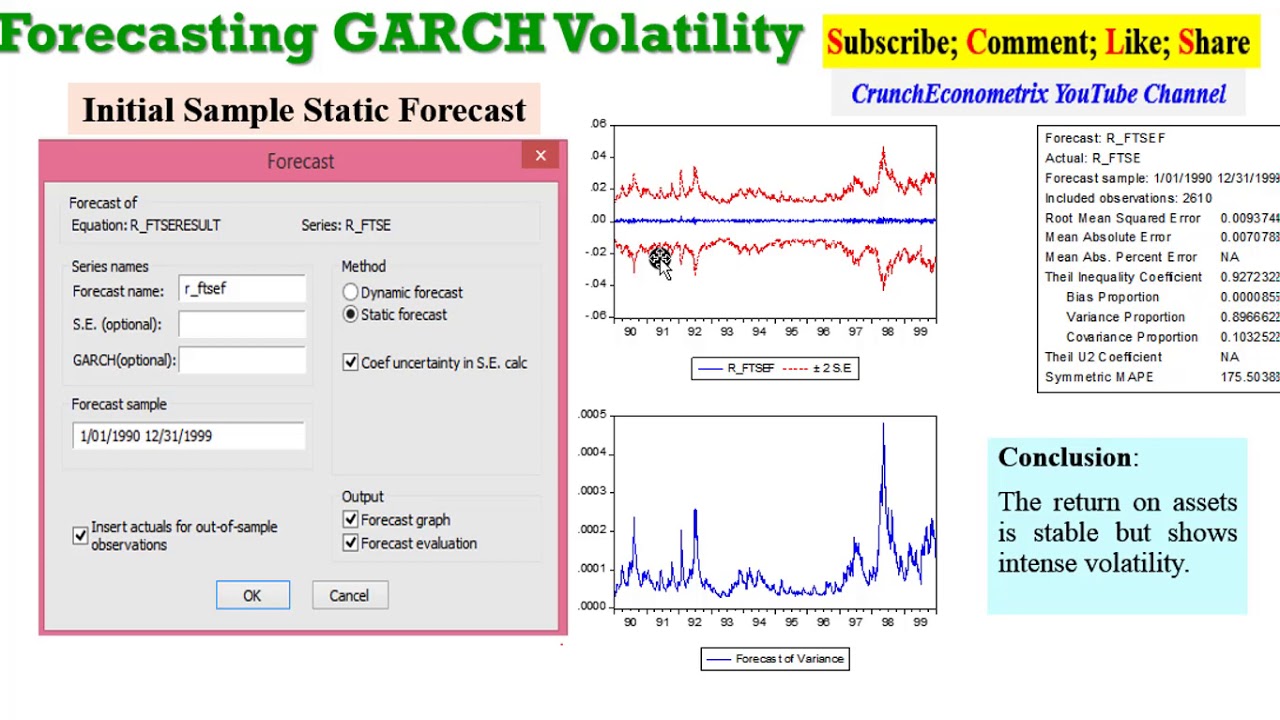
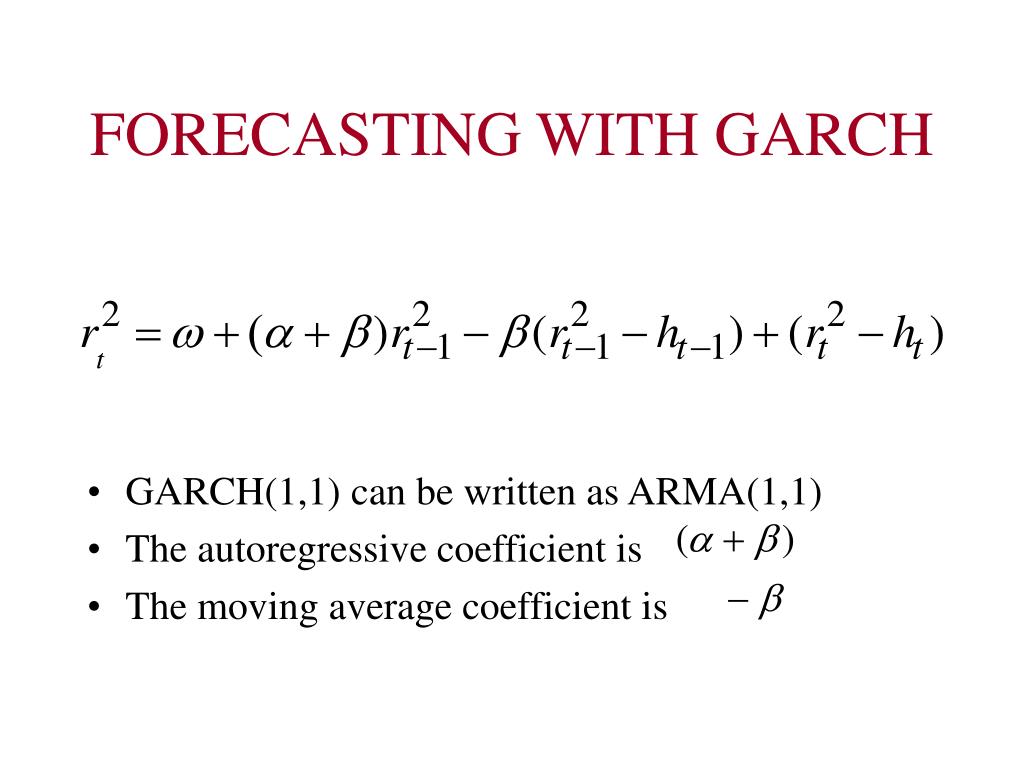
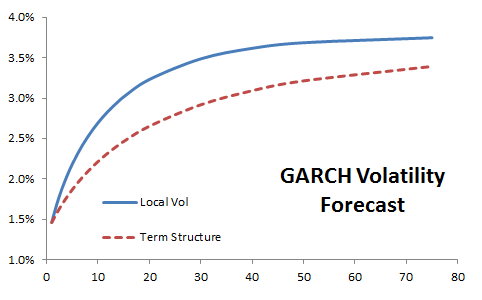
(EViews10): Forecasting GARCH Volatility #forecast #garchforecasts # ...
Volatility Forecasting - A Performance Measure of Garch Techniques With ...
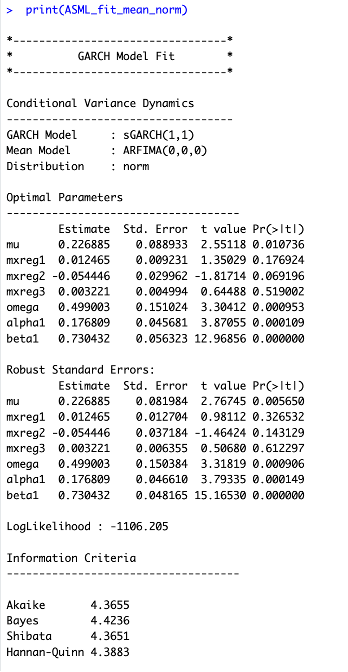
Estimating parameters of GARCH (1.1) model with normal distribution ...
The results of the estimation of the model DCC GARCH [1.1] | Download ...
time series - How to detect GARCH parameters must be updated? - Cross ...
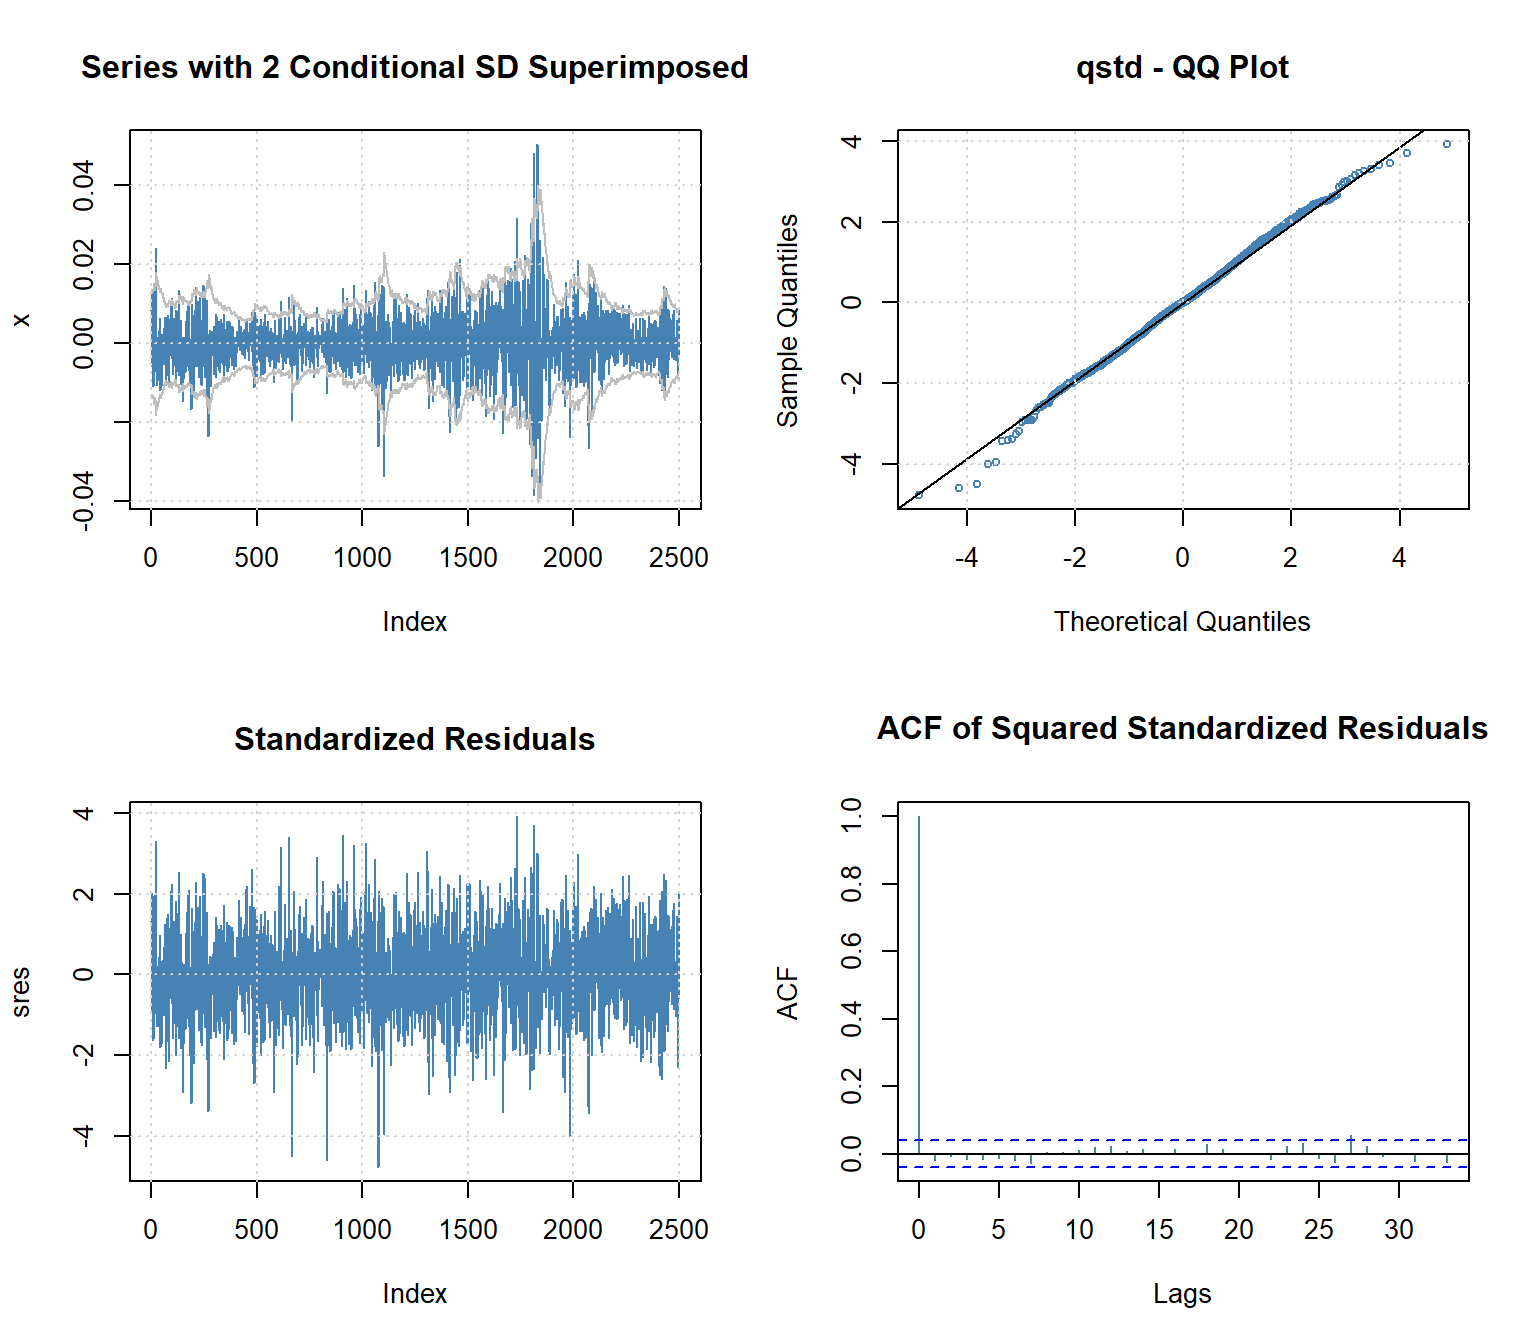
r - How to plot GARCH model volatility against the time series data ...
GARCH Volatility Models: Capturing Time-Varying Market Risk ...
How To Interpret Garch | Estimation of GARCH Models in OxMetrics – GWRNJD
Garch Model: Simple Definition - Statistics How To
Performance of the Realized-GARCH Model against Other GARCH Types in ...
Applying GARCH and INGARCH models to papal conclaves
Autocorrelation Function of Component GARCH and GARCH(1,1). Estimates ...
GARCH Interpretation : r/stata
Estimation result of GARCH models: Crude oil Source: Authors ...
Symmetric and Asymmetric Multivariate GARCH Models Parameter Estimates ...
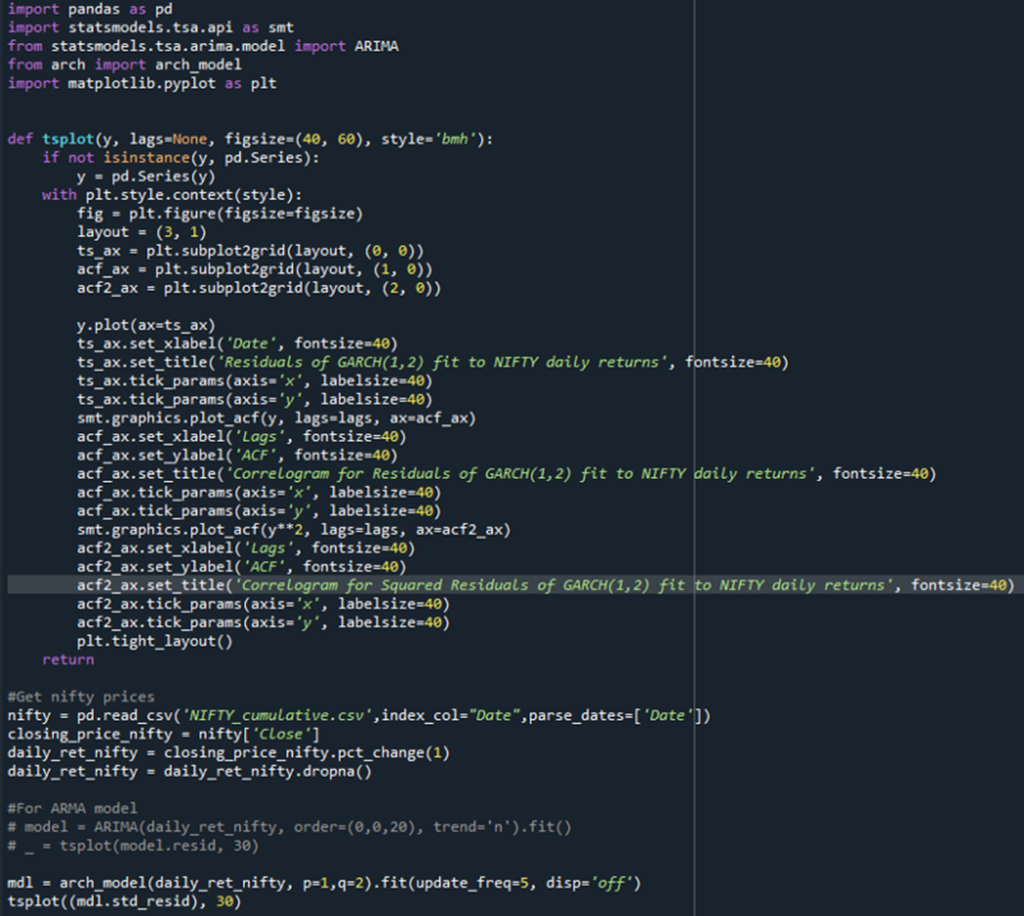
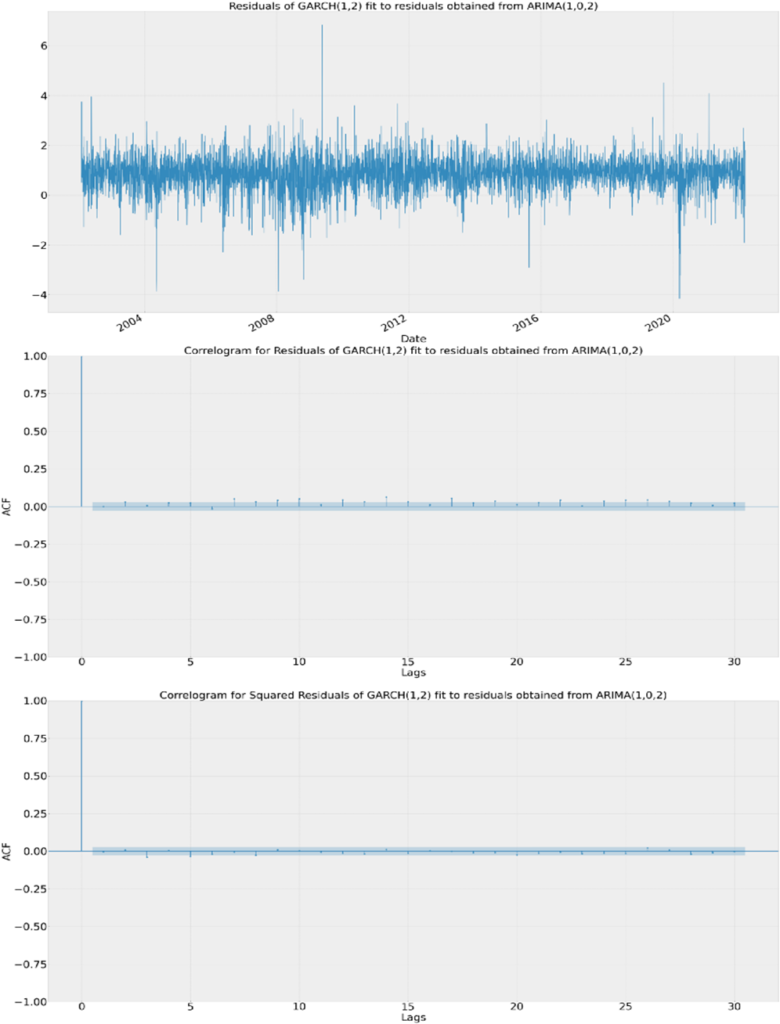
Modeling Volatility Clustering using GARCH model for NIFTY index
Estimated GARCH Parameters for Interbank Markets in the United States ...
GARCH model and statistical characteristics of implied volatility ...
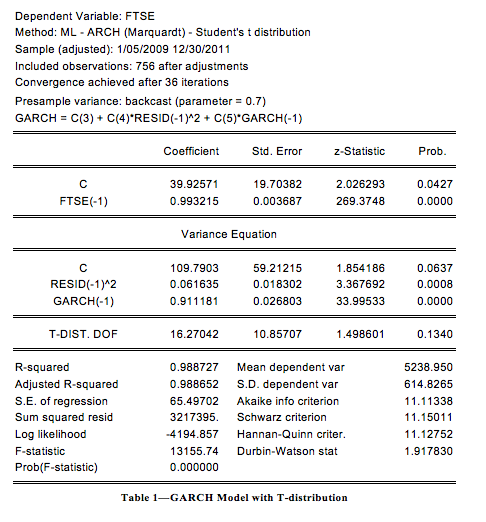
Estimated Coefficients of GARCH Models | Download Scientific Diagram
Garch Plot 例題 _ Garch 分析方法 – Forecasting Using Garch Model – IPJY
Regression Results: GARCH Estimation | Download Scientific Diagram
GARCH model - volatility persistence in time series (Excel) - YouTube
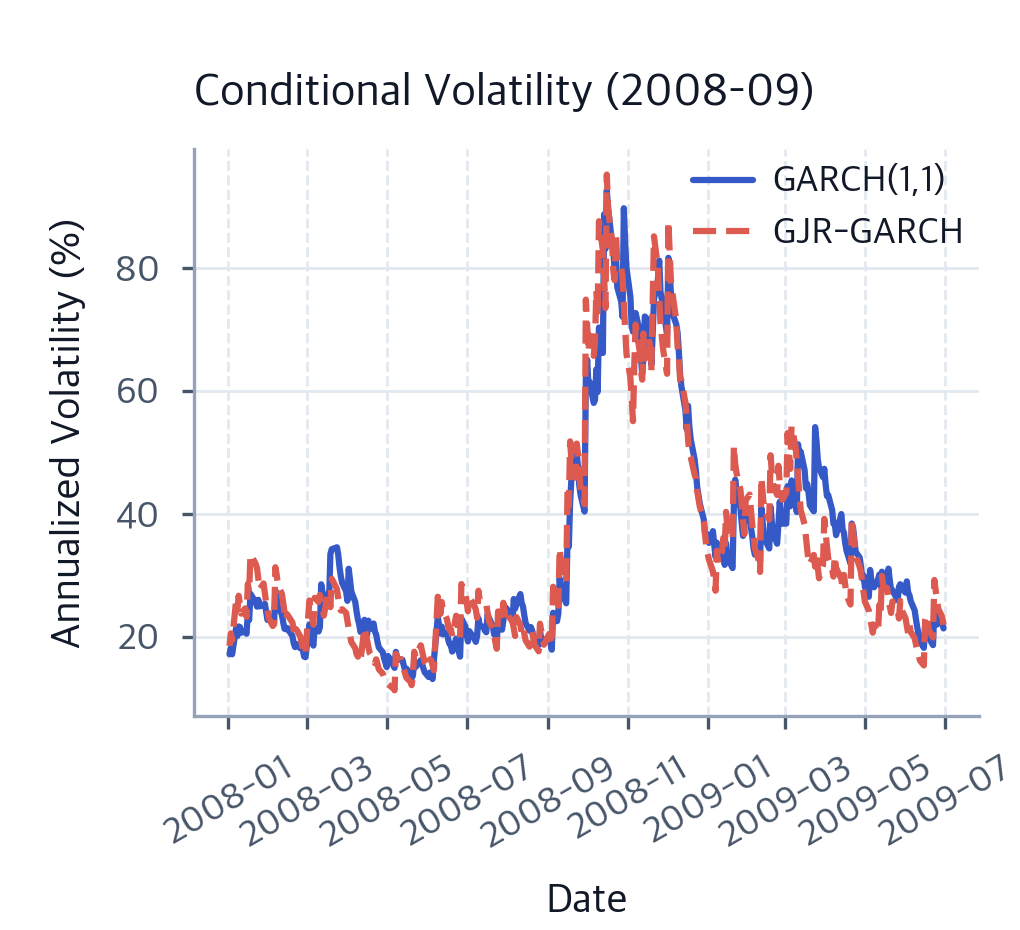
GARCH vs. GJR-GARCH Models in Python for Volatility Forecasting
Modelling Volatility: Arch And Garch Models – HBYRGQ
time series - Explosive Nature of GARCH (1,1) Model - Cross Validated
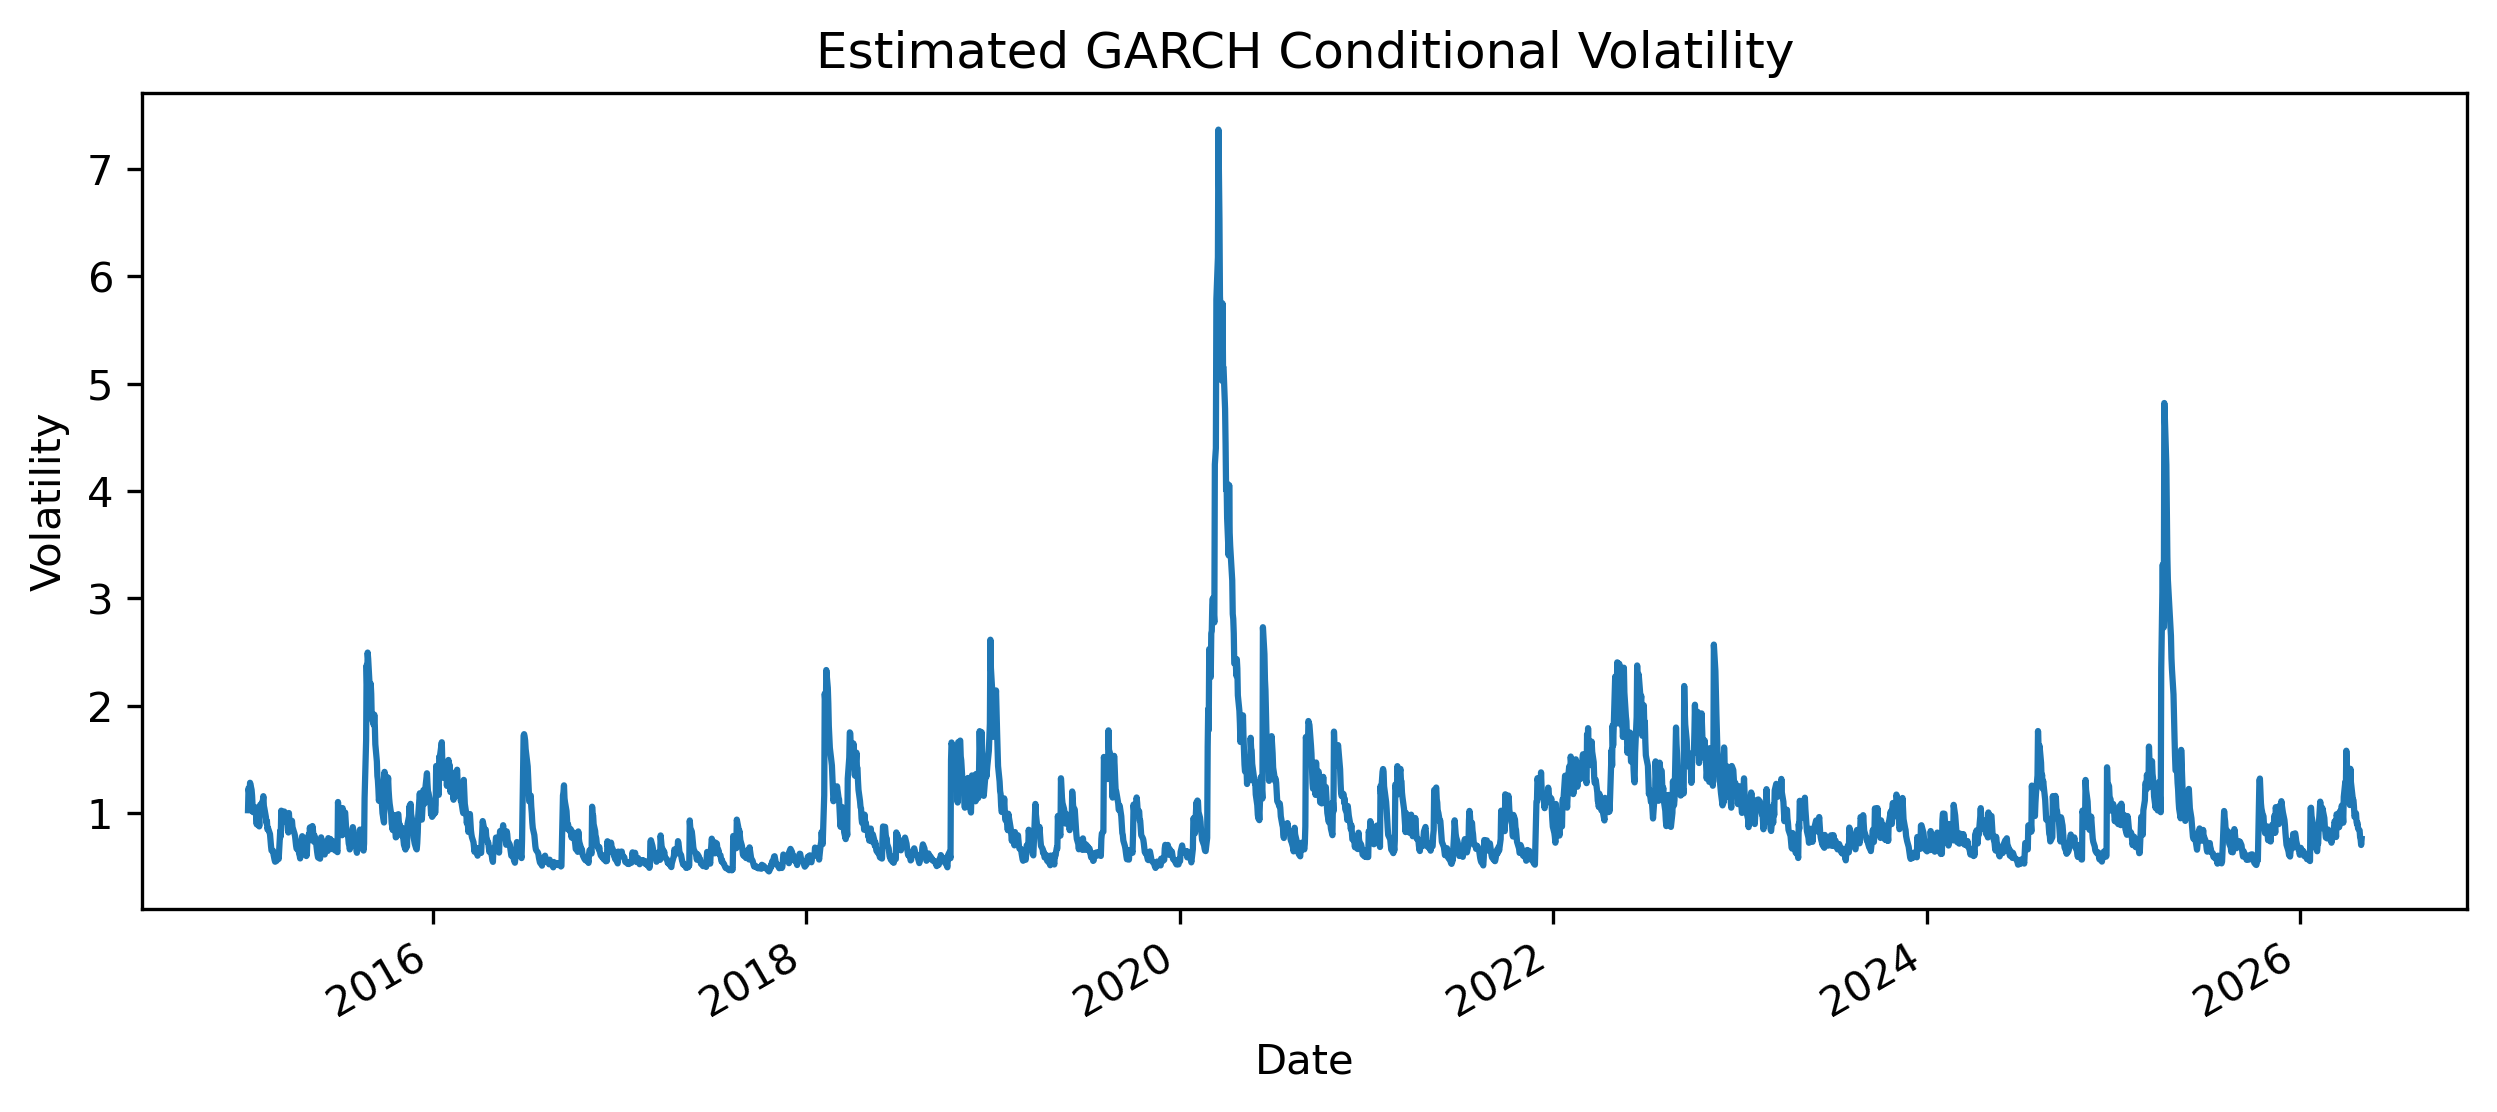
GARCH Volatility Estimation - The Quant Science — Indicator by ...
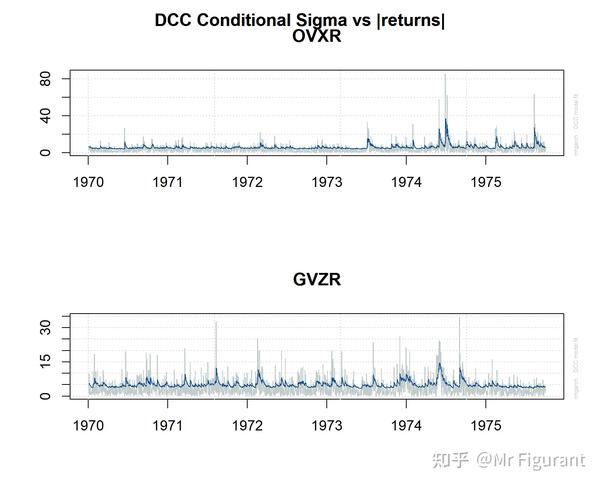
R语言实战 (9) | 时间序列分析 (5) -- ARCH 和 GARCH - 知乎
(PDF) Performance of the Realized-GARCH Model against Other GARCH Types ...
GitHub - DavidAlexanderMoe/Financial-Time-Series-Analysis-and ...
Part VIII Capstone — Forecasting Volatility and Financial Risk ...
garch11_model · InferHub
Models of Volatility Clustering: EWMA and GARCH(1,1) | Finance Train
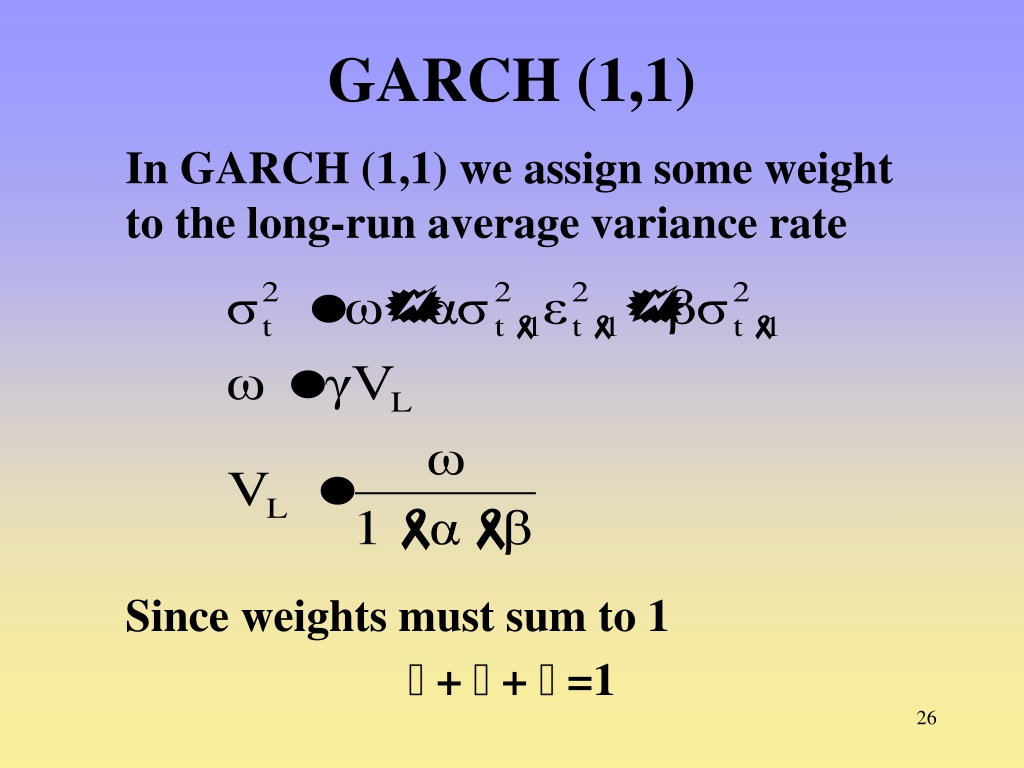
PPT - VOLATILITY MODELS PowerPoint Presentation, free download - ID:533275
PPT - Mastering Volatility Models for Financial Forecasting PowerPoint ...
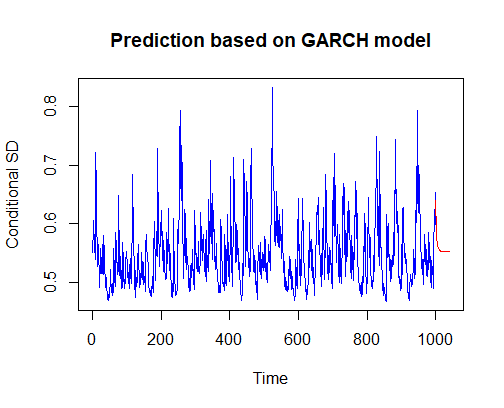
volatility - GARCH(1,1) forecast plot in R with training data ...
PPT - Volatility PowerPoint Presentation, free download - ID:9413319
PPT - Volatility Models PowerPoint Presentation, free download - ID:6637605
PPT - Estimating Volatilities and Correlations PowerPoint Presentation ...
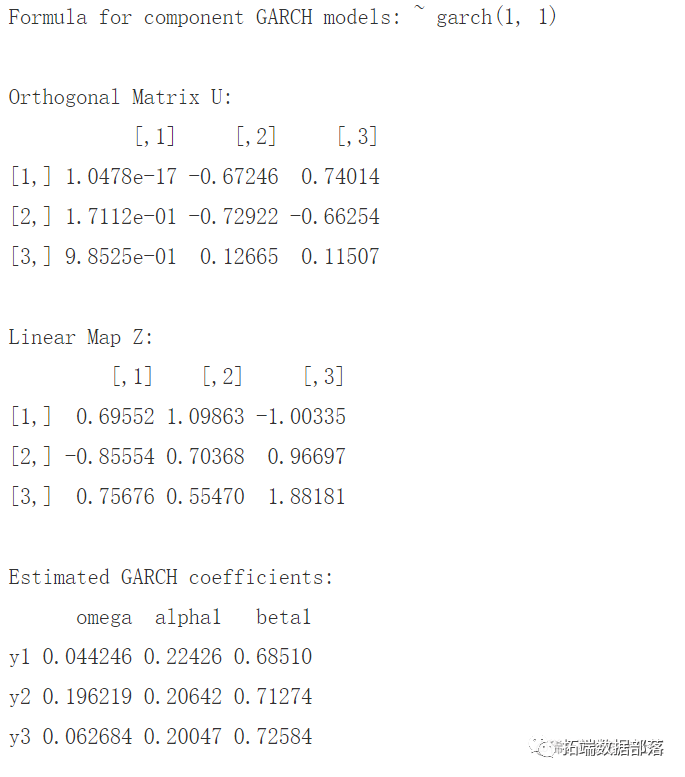
R语言多元(多变量)GARCH :GO-GARCH、BEKK、DCC-GARCH和CCC-GARCH模型和可视化|附代码数据-腾讯云开发者社区-腾讯云
3.4 Generalized Autoregressive Conditional Heteroskedasticity (GARCH ...
PPT - Stochastic Volatility Model: High Frequency Data PowerPoint ...
PPT - VOLATILITY MODELS PowerPoint Presentation, free download - ID:6789600
Time Series Analysis - 6 Generalized Autoregressive Conditional ...
Sarveshwar Inani's Blog: September 2016
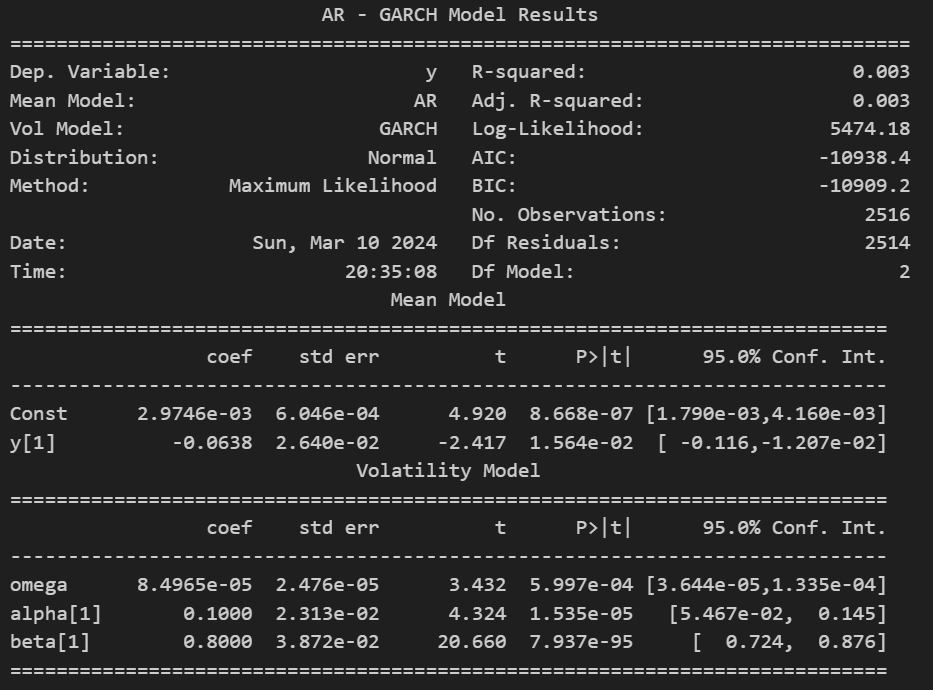
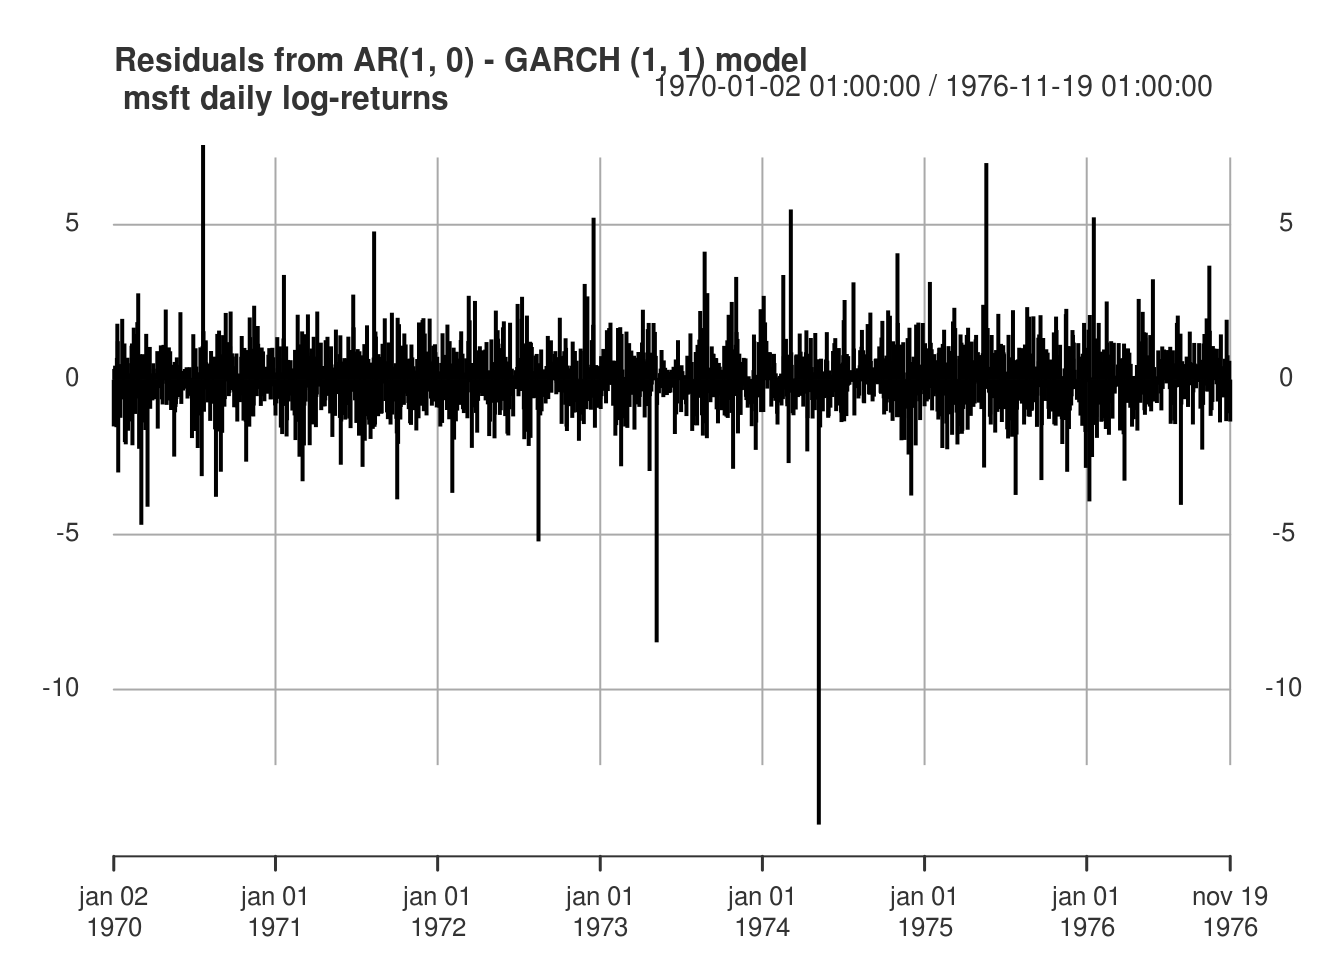
Model GARCH(1,1) AR(1) | Download Scientific Diagram
Volatility forecasting (GARCH & ARCH) - Nixtla
Characterizing and Modeling a Time-varying Volatility Time Series with ...
Arch Model Explained at Priscilla Carollo blog
GitHub - KinH8/Realized-GARCH: Incorporating a realized measure of ...
Plot of closing returns versus inferred volatility (GARCH ...
Procedure For Fitting An Arma/Garch Model – ZYEL
PPT - Possible Research Interests PowerPoint Presentation, free ...
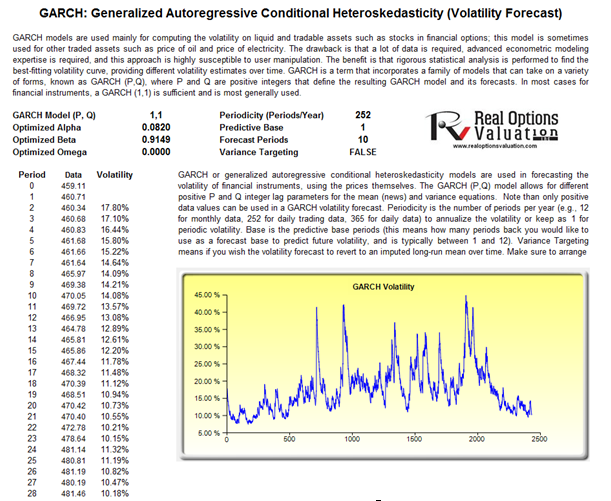
Volatility – Volatility Computations – ROV
How should I interpret the resulting coefficients in the conditional ...
Volatility Modelling and Hedging Analysis | PPTX
各类GARCH模型 - 知乎
Figures index : A Comparative Study of Volatility of Consumer Price ...
时间序列--GARCH模型 - 知乎
Estimated parameters in the GARCH(1,1) specification. | Download ...
PPT - Volatility in Financial Time Series PowerPoint Presentation, free ...
Value-at-Risk Analysis for Measuring Stochastic Volatility of Stock ...
PPT - Volatility PowerPoint Presentation, free download - ID:3119614
Module 8 - Forecasting – Help center
Actual volatility versus GARCH(1,1) and GARCH(1,1) with an adaptive ...
R语言学习:如何构建DCC-GARCH模型? - 知乎
Summary Statistics of Stock Return | Download Scientific Diagram
R语言软件套保期限GARCH、VAR、OLS回归模型对沪深300金融数据可视化分析-腾讯云开发者社区-腾讯云
PPT - Estimating Volatilities and Correlations Chapter 21 PowerPoint ...
PPT - Modeling and Forecasting Stock Return Volatility Using a Random ...
基于GARCH类模型的人民币汇率波动特征分析_参考网
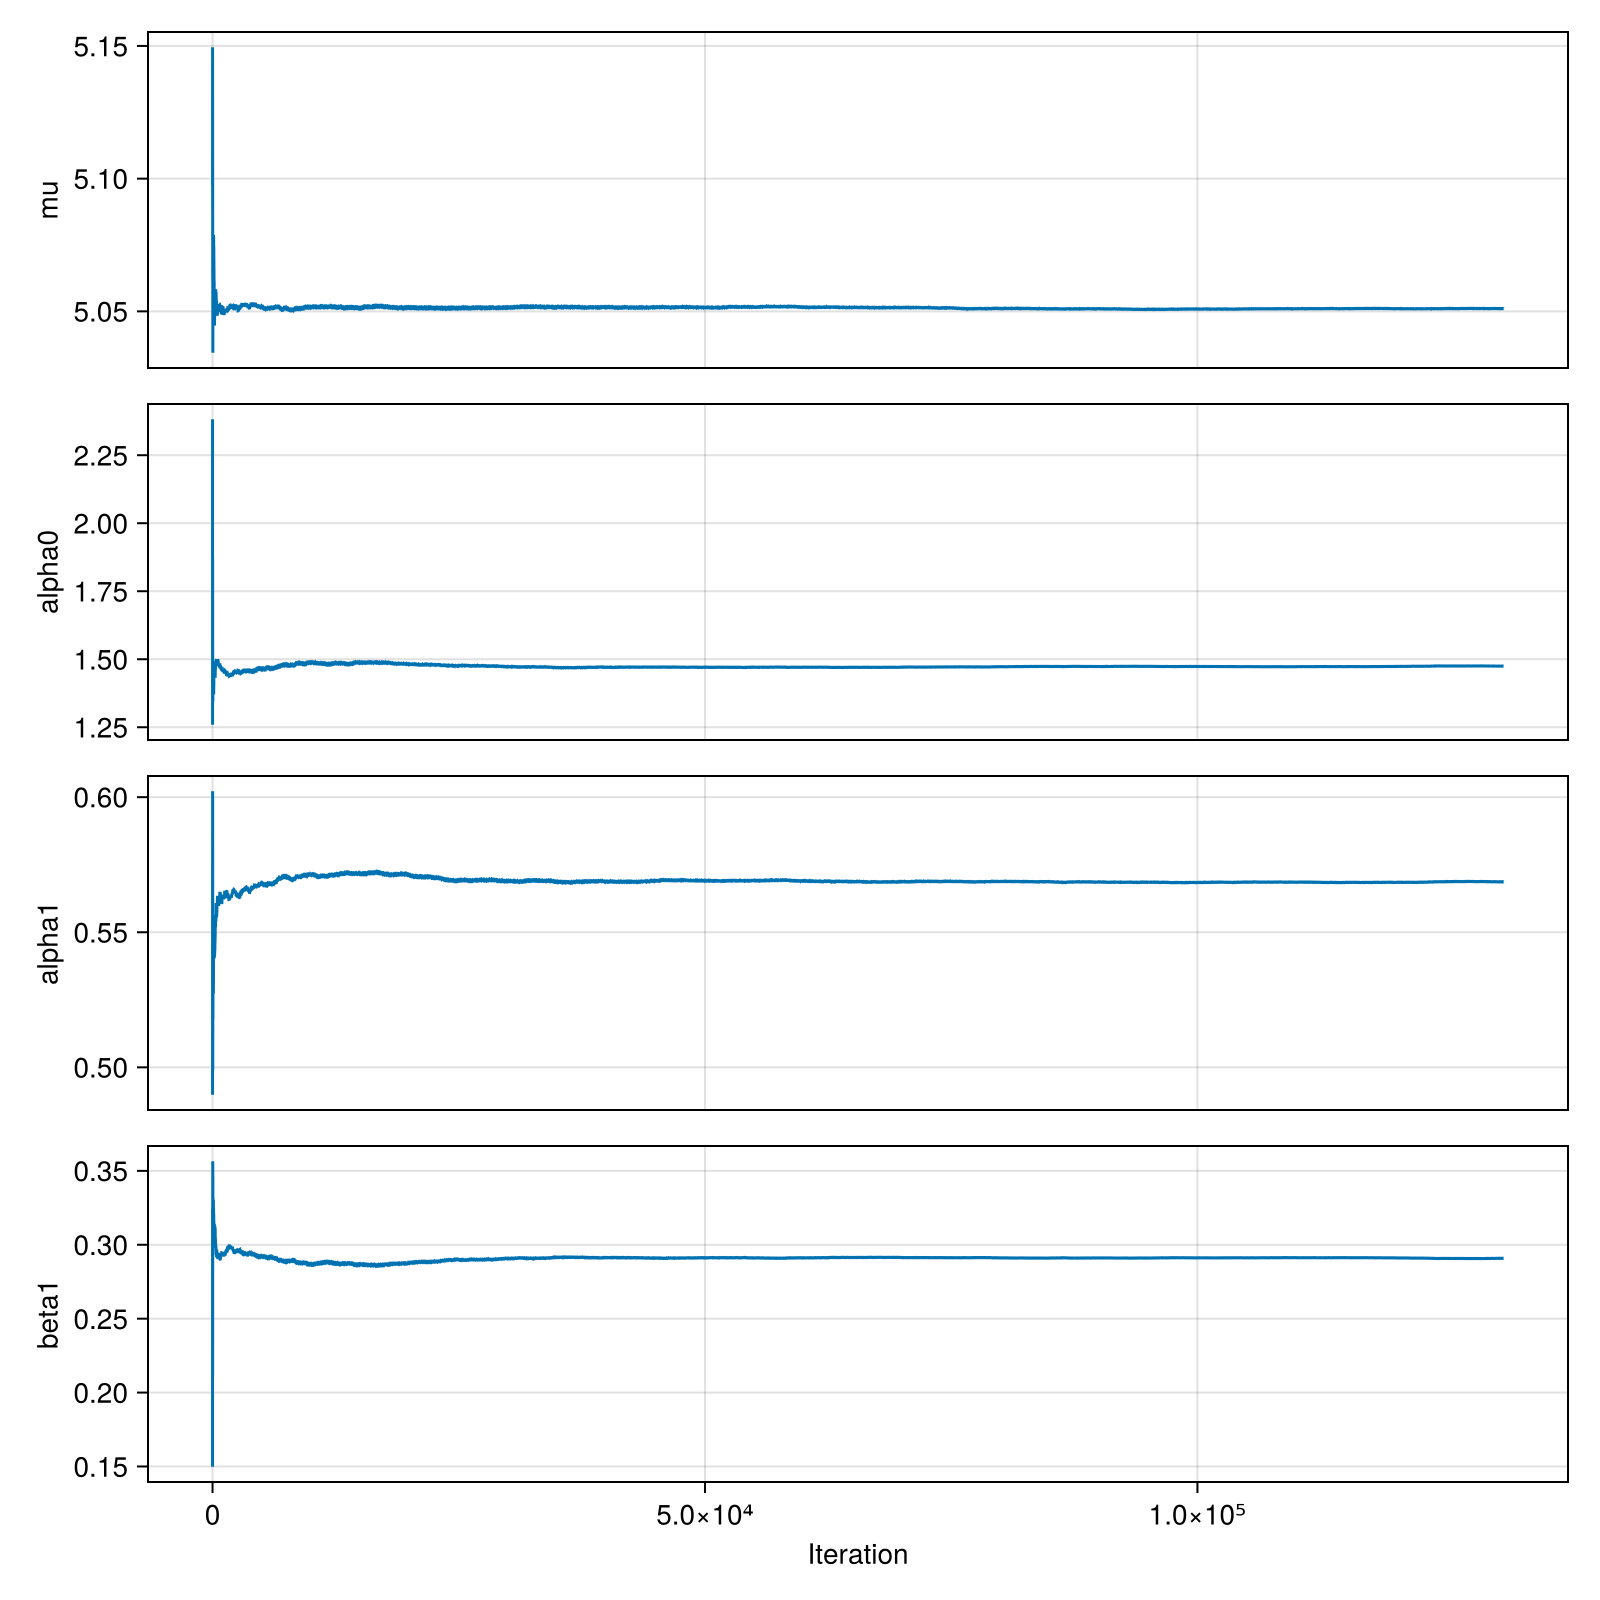
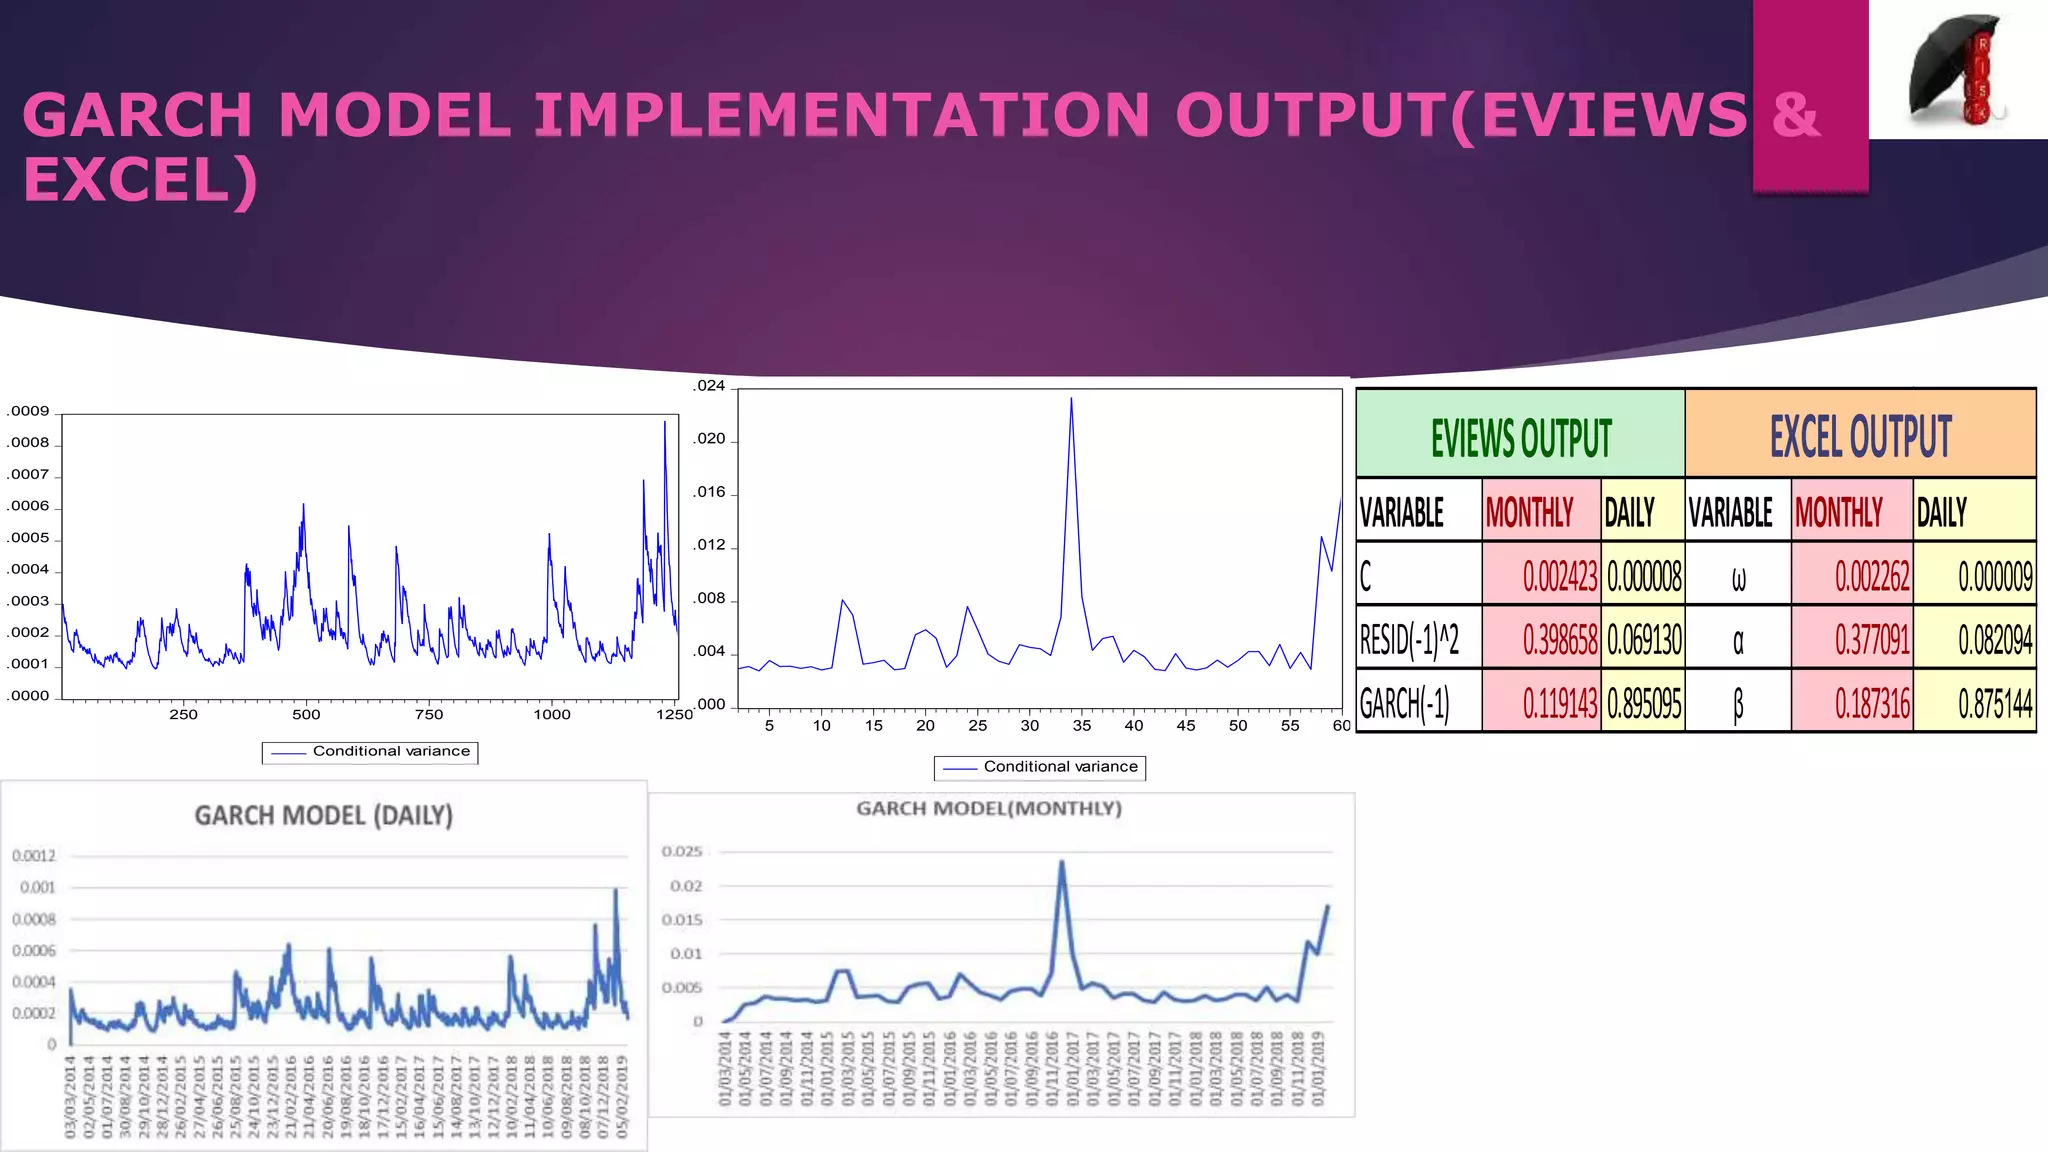
The GARCH(1,1) model estimation | Download Scientific Diagram
Volatility extracted from AR(1)-GJR-GARCH(1,1) model for S&P 500 ...
Comparison of one-step-ahead volatility forecasts for GARCH(1,1) and ...
Volatility extracted from AR(1)-GJR-GARCH(1,1) model for US 10-Year ...
model evaluation - How to compare the performance of a volatility ...
ARCH and GARCH. Modeling Volatility Dynamics - online presentation
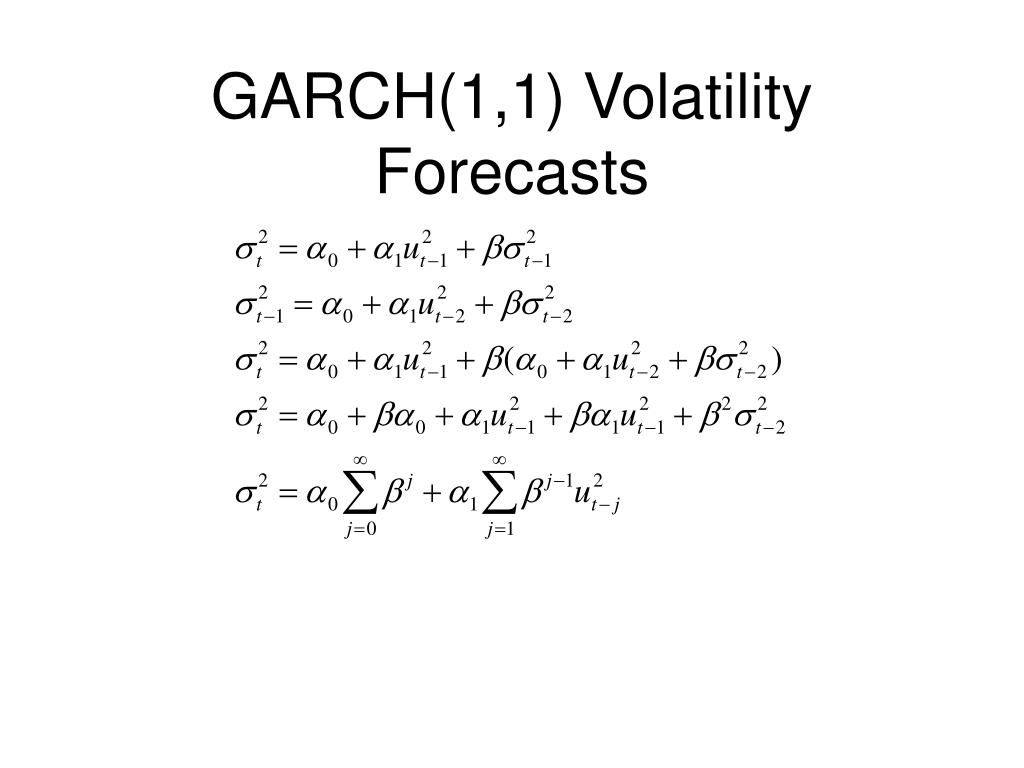
Properties and Estimation of GARCH(1,1) Model
PPT - Modeling of Variance and Volatility Swaps for Financial Markets ...
Volatility modelling and coding GARCH(1,1) in Python | by Teckk | Medium
maximum likelihood - Modelling time varying volatility when GARCH(1,1 ...
time series - How to model a GARCH(1,1) with covariate? - Cross Validated
(PDF) Modeling of Returns Volatility using GARCH(1,1) Model under Tukey ...